
-
AuthorSearch Results
-
August 4, 2025 at 3:18 pm #28395
In reply to: Forex Forum
What’s hot and wgst’s not?
What’s hot?
US stocks having a sharp rebound, recovering some of Friday s selloff
Gold extends its rebound (briefly so far through 3377)
What’s not?
News algos having a lack of market moving headlines.
CHF is weaker as USDCHF remains the outperformer
What’s hot/not?
Dollar trading mixed with follow through so far limited (except USDCHF)
US bonds flipping between bid and offered, currenly unchanged.
 August 4, 2025 at 12:45 pm #28382
In reply to: Forex Forum
August 4, 2025 at 10:44 am #28371In reply to: Forex Forum
August 4, 2025 at 9:31 am #28367In reply to: Forex Forum
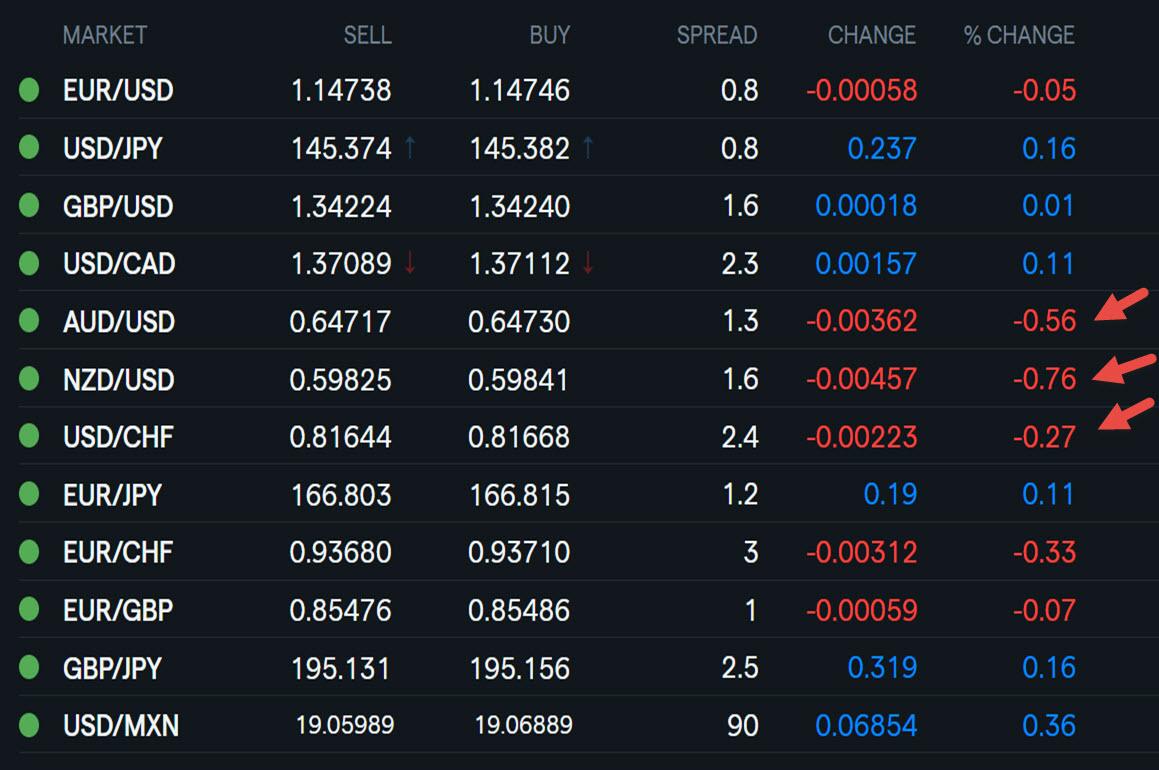
Using my platform as a Heatmap shows
No aftershocks following Friday’s market earthquakes that saw the dollar and stocks tumble
The dollar is off opening week lows as it consolidates but still feeling effects if its tumble
EURUSD so far holding 1.1550
USDJPY briefly tested 148+
CHF is the underperformer (USDCHF up over 0.6%)
Gold is consolidating as well after rising sharply on Friday
US stocks have recovered some of Friday’s losses
US bond yields are up a touch after plunging on Friday on raised expectations of a Sept rate cut
 June 19, 2025 at 9:34 am #26473
In reply to: Forex Forum
Using my platform as a HEATMAP shows
Risk off as Trump weighs whether or not to get involved in the Iran-Israel war.
The dollar trading firm but retreating from overnight highs
A firmer safe haven CHF is an exception with USDCHF trading lower despite (as expected) SNB cutting rates to zero
Gold bouncing from its low as it attempts to regain a safe haven bid
US stock markets are closed for a U.S. holiday but CFDs are lower
Crude oil ia higher
Next up: UK rate decision
US markets are closed for the Juneteenth holiday
 June 16, 2025 at 4:59 pm #26348
In reply to: Forex Forum
SocGen’s Economic News Summary
Societe Generale in its early Monday economic news summary pointed out:
— Risk aversion subsides, S&P futures +0.2%, USDCHF steady at 0.8110. Yields up led by Australian government bonds (10-year +8bps), United States Treasury +3bps to 4.42%.
— European Central Bank’s de Guindos: tariffs will weigh on eurozone economic growth and prices for years, but there is little risk of inflation falling too low, euro surge against the US dollar isn’t a major worry.
— China’s retail sales surprise to the upside in May, Q2 gross domestic product tracking 5%. Industrial production eased to 5.8% year over year, FAI year-to-date 3.7%. Retail sales accelerate to 6.4% on Labor Day holiday, consumption subsidies and earlier start of 618 shopping festival. Property investment slump worsens to -10.7% year over year. USDCNY bid at 7.1850. 10-year CGB yield flat at 1.70%.
— CFTC weekly positioning: long euro raised to 11.5%, long yen trimmed to 37.3%, long sterling upped to 24.1%, short Canadian dollar (CAD or loonie) cut to 32.3%, Australian dollar shorts steady at 31.2%, short Swiss franc drop to 32.3% and long Mexican peso trimmed to 34.7%.
— Week ahead: G7 in Canada, Federal Reserve to stand pat, update forecasts and dot-plot. U.S. retail sales. Bank of Japan, Bank of England, Norway’s Norges Bank, Turkey, Taiwan, Brazil and Indonesia central banks forecast to keep rates on hold. Swiss central bank (SNB) forecast to cut 25bps, Sweden’s Riksbank 25bps cut in the balance. Final eurozone and United Kingdom consumer price index. Chinese banks to leave the one- and five-year LPRs unchanged at 3.0% and 3.5%.
— Nikkei +1.1%, EUR 10-year IRS +3bps at 2.59%, Brent crude +0.5% at $74.6/barrel, Gold -0.5% at $3,416/oz.
Nikkei chart
 May 12, 2025 at 9:21 pm #24749
In reply to: Forex Forum
May 12, 2025 at 10:24 am #24703In reply to: Forex Forum
May 12, 2025 at 9:32 am #24699In reply to: Forex Forum
April 13, 2025 at 8:59 pm #22583In reply to: Forex Forum
April 9, 2025 at 6:28 pm #22382In reply to: Forex Forum
AnonymousApril 9, 2025 at 3:30 pm #22380In reply to: Forex Forum
“This seemingly ‘sell America’ trade is one that’s now dominating the rising recession risk theme that typically would have pushed yields down,” economists at ING said.
The dollar – often a safe haven in times of turmoil – fell broadly, while investors fled to the Swiss franc and gold.
The dollar index DXY, which measures the greenback against a basket of currencies including the yen and the euro, fell 0.5% to 102.26, with the euro EURUSD up 0.78% at $1.1037. Against the Japanese yen USDJPY, the dollar weakened 0.98% to 144.84.
Against the Swiss franc USDCHF, the dollar weakened 1.01% to 0.839. Spot gold class=”logo-PsAlMQQF xxxsmall-PsAlMQQF letter-PsAlMQQF” crossorigin=”” v:shapes=”_x0000_i1032″>GOLD rose 3.03% to $3,074.35 an ounce.
The yield on benchmark U.S. 10-year notes US10Y rose 12.4 basis points to 4.384%, from 4.26% late on Tuesday.
Potentially adding to the pressure on Treasuries was an auction of new 10-year notes later on Wednesday – hot on the heels of a weak three-year sale the day before – that could prove a crucial litmus test of investor appetite for U.S. government debt.
US STOCKS RISE EARLY
U.S. stocks were in positive territory early, with investors weighing whether recent sharp selling may have been overdone, although trading remained choppy as it has been all week.
April 7, 2025 at 5:39 pm #22196In reply to: Forex Forum
Investors pile into safe-haven currencies as tariff worries ripple through markets
Key points:
· Investors scoop up the yen and Swiss franc
· Aussie steadies after hitting five-year low
· Markets leaning toward Fed cut in May
Investors bought into safe havens such as the dollar, yen and Swiss franc on Monday as concerns about a global recession heightened following U.S. President Donald Trump’s sweeping tariffs on trading partners.
· Global markets plunged on Monday, with Wall Street stocks trading lower after Asian shares sank, as investors wagered the mounting risk of a deep economic downturn could lead to a cut in U.S. interest rates as early as May.
· The risk-sensitive Australian and New Zealand dollars, as well as the Swedish and Norwegian crowns, all dropped against the dollar.
· The dollar cut its losses against other safe-haven currencies. It was up 0.50% against the yen USDJPY to 147.605, after tumbling more than 1.4% earlier in the session.
· The dollar also hit its lowest in six months against the Swiss franc and was last down 0.06% at 0.8605 franc in choppy trading. USDCHF.
· “The only thing we know for sure is that it’s volatile … But I think broadly, leaving aside nuances, because tariffs are thought to be hurting world growth, those currencies that seem to be more like risk-on currencies – the dollar bloc and the Scandies – they are underperforming,” said Marc Chandler, chief market strategist at Bannockburn Global Forex in New York.
· “On the other hand, the currencies that are typically safe-haven currencies – like the Swiss franc and yen – are performing better.”
· The euro EURUSD, which gained as much as 0.7% to $1.1050 earlier in the session, was down 0.39% at $1.091775.
· “The euro has certainly performed really quite well over the last couple of days since we’ve heard about the tariffs,” said Jane Foley, head of FX strategy at Rabobank.
· “Maybe that’s related to the euro zone current account position, or maybe it’s just related to investors still moving out of U.S. assets and still not quite sure where they should be moving their money to.”
While the dollar is typically known as a safe-haven asset, that status seems to be eroding as uncertainty over tariffs and concern over their impact on U.S. growth intensify.
Brought to you by Reuters
January 22, 2025 at 7:08 pm #18235In reply to: Forex Forum
I am expecting US stocks to temporarily run into trouble in the next day or so and that should affect Euro’s performance as well. USD still has room to run but it is getting steep in the broader picture and so I think that is worth considering if holding positions. Eventually, but not anytime soon, I expect we see UsdChf 0850 again.
December 13, 2024 at 9:12 am #16197In reply to: Forex Forum
December 9, 2024 at 2:12 pm #15922In reply to: Forex Forum
SO FAR entering the week. I like Australian Dollar, Sterling, to a lesser extent Swiss Franc, and depending on a few things Euro on dips but my preferred side with that one still is the sell side. The buy side of Yen pairs is the best for me entering the week. UsdChf is bottoming in likelihood, but there could be another little stop run downhill prior from here.
December 3, 2024 at 4:40 am #15462In reply to: Forex Forum
December 2, 2024 at 4:16 pm #15410In reply to: Forex Forum
November 29, 2024 at 4:23 pm #15283In reply to: Forex Forum
November 29, 2024 at 2:16 pm #15275In reply to: Forex Forum
The standout positive I see today is the president of Mexico stating a tariff war can be averted since her meeting with Trump. The other wars are still present and it appears the Lebanon ceasefire has already been breached. So the unsettled Geo condition prevails for now. All things considered I am patiently waiting for UsdChf to pull up for a sell side entry but not sure we get enough movement today.
One might expect a stock picking environment today.
November 26, 2024 at 6:03 pm #15133In reply to: Forex Forum
November 26, 2024 at 3:02 pm #15097In reply to: Forex Forum
November 26, 2024 at 2:31 pm #15087In reply to: Forex Forum
Nothing has changed in the dominant US Dollar dynamic. The market is simply rebalancing after yesterday’s run. There are good buy side trades coming up if you are patient. Use USDSgd 1.3430 as a reference point of where larger sized entities maybe. And if you do not trade UsdChf (Franc) you can use it as a guage as well with an eye on 8830. On a fundamental basis, yesterday’s run was fundamental news driven but without proof, hence the rebalancing. In time markets will reconsider and make the “what if” adjustment right back up. Give it time. I scored/booked 295 points since Sunday in multiple currency pairs, I am fairly precise right now.
November 26, 2024 at 12:30 am #15055In reply to: Forex Forum
I just closed sell side positions of EurJpy, EurUsd, AudUsd, UsdSingapore, and a buy side UsdChf right here, and a sell EurGbp all in the money. These levels as I type are areas where I believe there may be adjustment flows and so it is back to a game of patience. Prefer buy side of US Dollar and the sell side of everything else so a matter of waiting for these markets to rebalance a bit.
Had a sell USdPeso but did not fill, not confident we see decent re-entry levels until tomorrow.
Honor the Dollar.
November 25, 2024 at 7:07 pm #15016In reply to: Forex Forum
November 25, 2024 at 10:31 am #14963In reply to: Forex Forum
November 21, 2024 at 7:39 pm #14837In reply to: Forex Forum
Something to consider is the cycling of big money. Today they are buying Dow stocks ahead of a Friday with a US holiday and major Geo risk. That is driving some currencies down which would otherwise move in tandem, but the money is not as happy outward with those currencies as they are with a 2025 stock rally.
There should be a delayed reaction which would support the sell side of UsdChf and other safe haven plants beginning either in Asia or Europe tonight.
Euro will likely not receive the same benefit as Swiss (futures especially) and so I am not biting here on any bear trap setup, although I might in other conditions. Better play, at least for me is the buy side of Swiss itself and Yen itself.
November 21, 2024 at 6:22 pm #14834In reply to: Forex Forum
November 19, 2024 at 3:16 pm #14650In reply to: Forex Forum
November 18, 2024 at 6:01 pm #14561In reply to: Forex Forum
-
AuthorSearch Results


Search
© 2024 Global View