
- This topic has 28,408 replies, 54 voices, and was last updated 4 minutes ago by Adam Global.
-
AuthorPosts
-
June 25, 2025 at 10:30 am #26710
SocGen’s Overnight Economic News Summary
— Risk tone positive, VIX below 18 after 12% drop yesterday, Nasdaq-100 closed at anew record. US dollar index skids below 98.0. FOMC pricing largely unchanged after Federal Reserve Chair Powell testimony, July steady at -5bps, September -25bps.
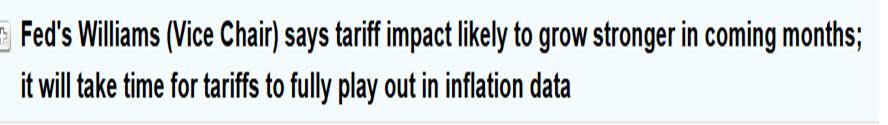
— Fed Chair Powell: expect to see meaningful tariff inflation effects in June, July, August. Williams (voter): maintaining modestly restrictive stance of monetary policy is entirely appropriate. Schmid (voter) backs wait-and-see approach.
— Australia’s consumer price index cools more than forecast to 2.1% year over year in May from 2.4% in April, core slow to 2.4% from 2.8%. Implied odds of July Reserve Bank of Australia cut climb to 93% from 84%.
— Day ahead: NATO summit. Fed Chair Powell repeats testimony to Senate, different question-and-answer session. United States new home sales, U.S. Treasury five-year auction. Bank of England’s Lombardelli. The Czech central bank (CNB) forecast to stay on hold.
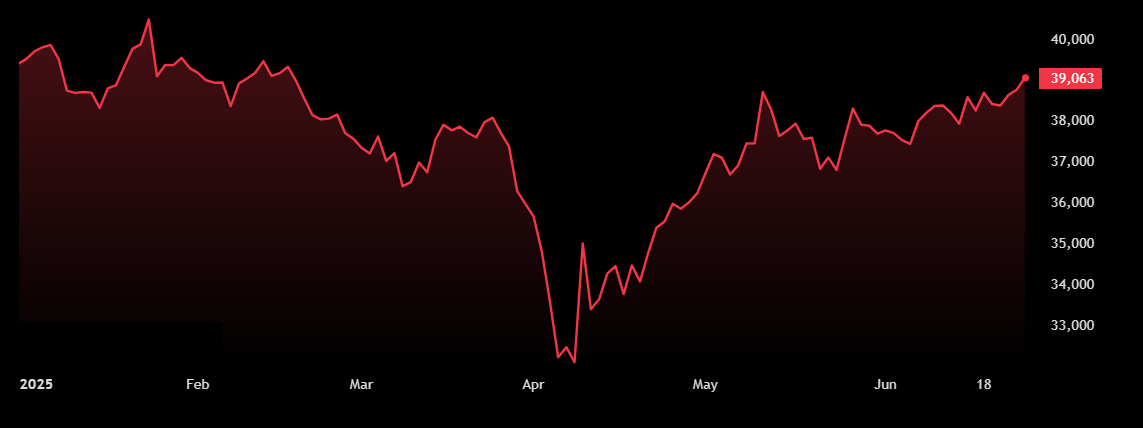
— Nikkei +0.3%, EUR 10-year IRS -1bp at 2.545%, Brent crude +1.6% at $68.2/barrel, Gold +0.4% at $3,330/oz.
Nikkei Chart
 June 25, 2025 at 10:11 am #26709June 25, 2025 at 10:07 am #26708June 25, 2025 at 9:20 am #26707
USDJPY
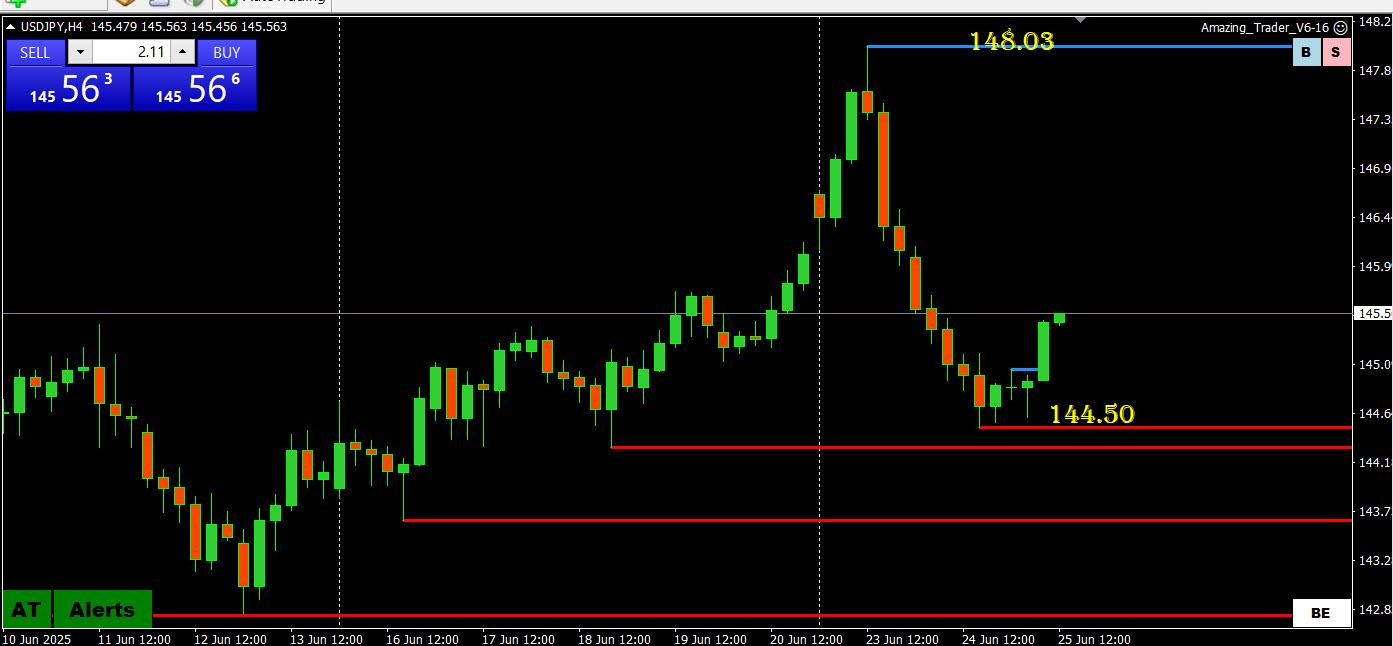
What caught my eye is the USDJPY low at 144.50, once again showing the Power of 50 level…Look at JPY crosses for a source of USDJPY demand
The one way move from 148.03 => 144.50 leaves little in the way of obvious resistance so let’s use retracements as potential levels
FIBOS FOR 148.03 => 144.50

USDJPY 4 HOUR CHART
 June 25, 2025 at 8:59 am #26706
XAUUSD (GOLD)
Consolidating
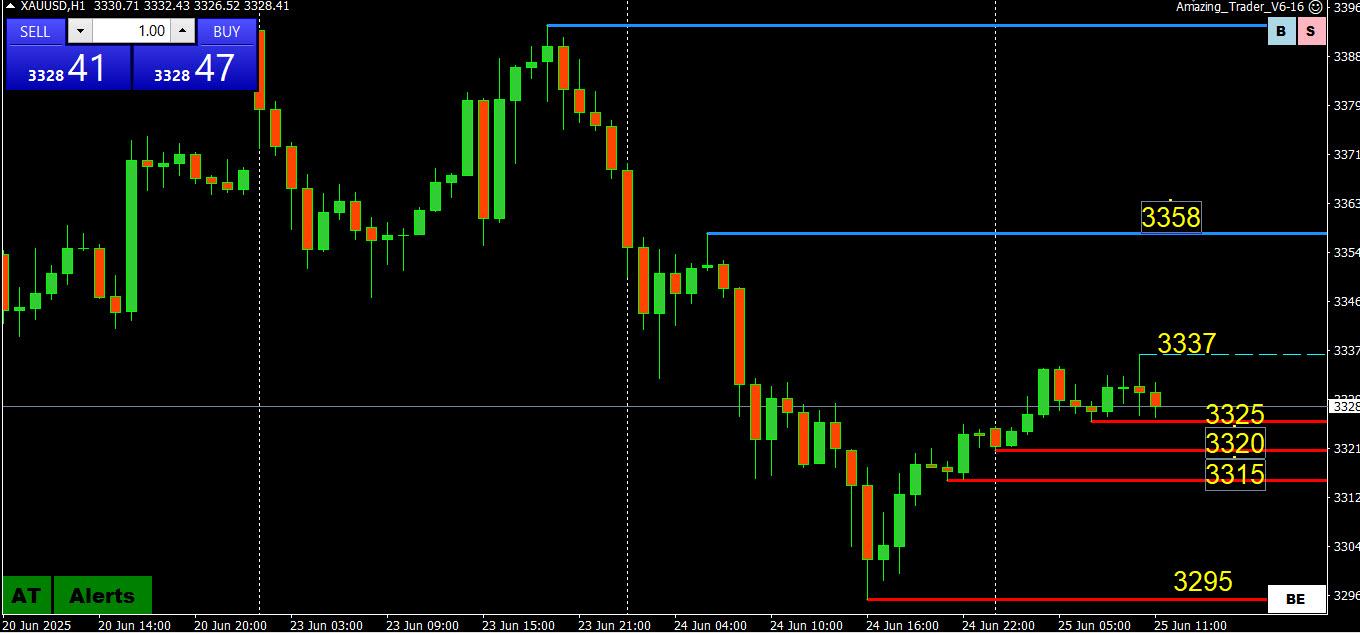
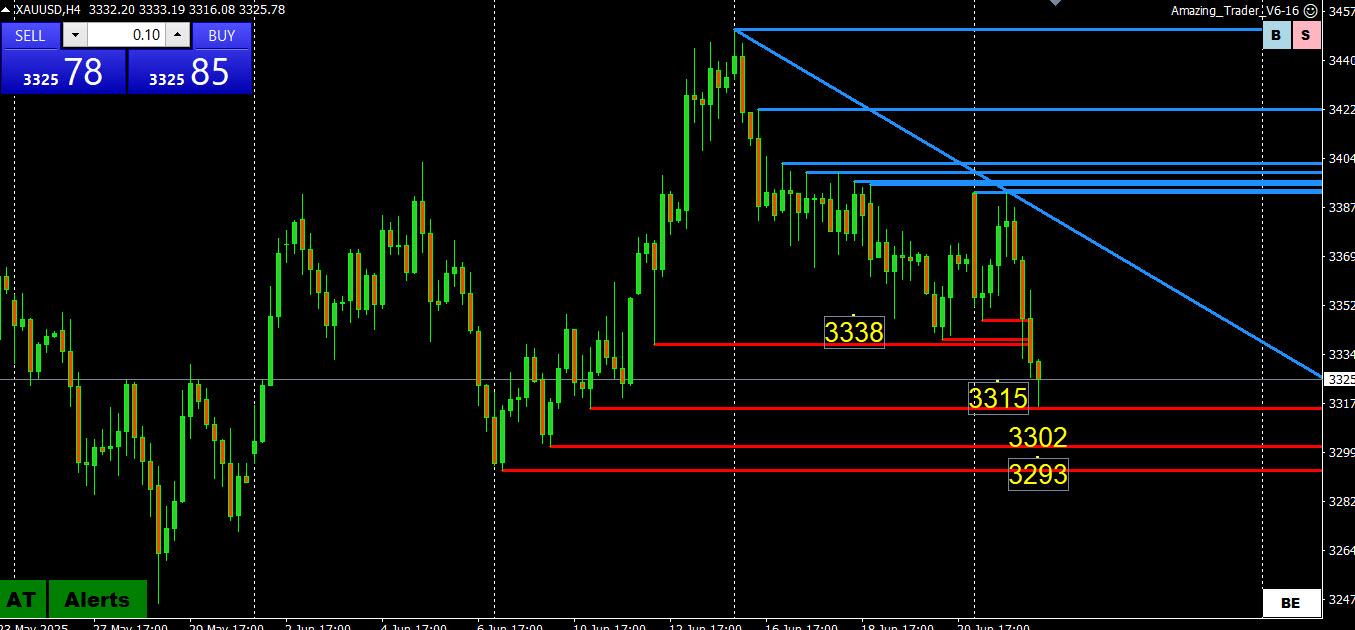
XAUUSD showing signs of a potential low after pausing $2 above my key 3293 support BUT
… would need to regain 3338-40+ to ease the risk… high so far today 3337
Above 3358 would then be needed to put 3400 back on the radar.
Supports between 3315-25 block exposing 3293-95 again.
XAUUSD DAILY CHART
 June 25, 2025 at 8:47 am #26705
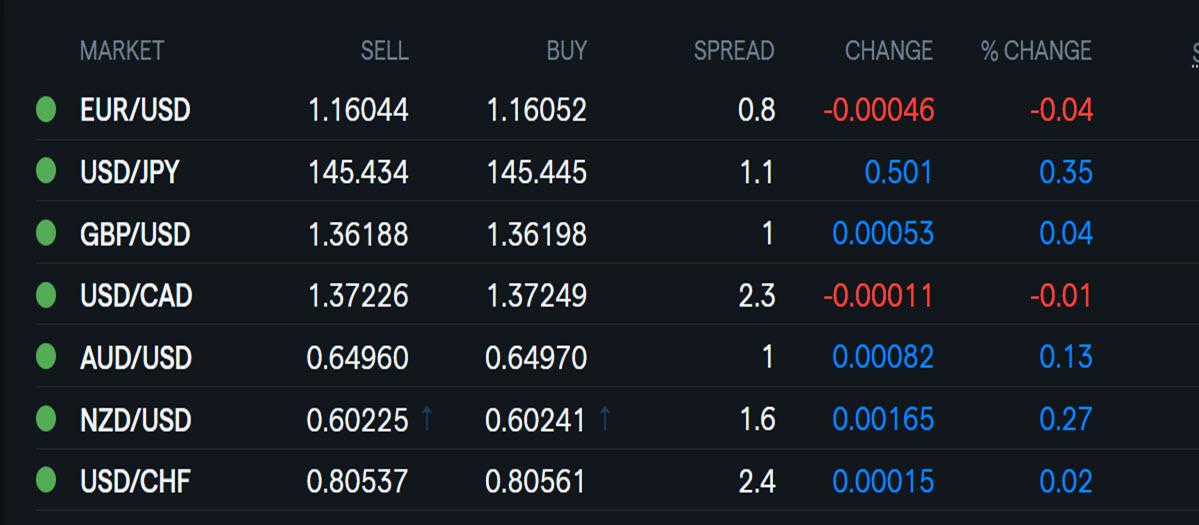
Using my platform as a HEATMAP shows
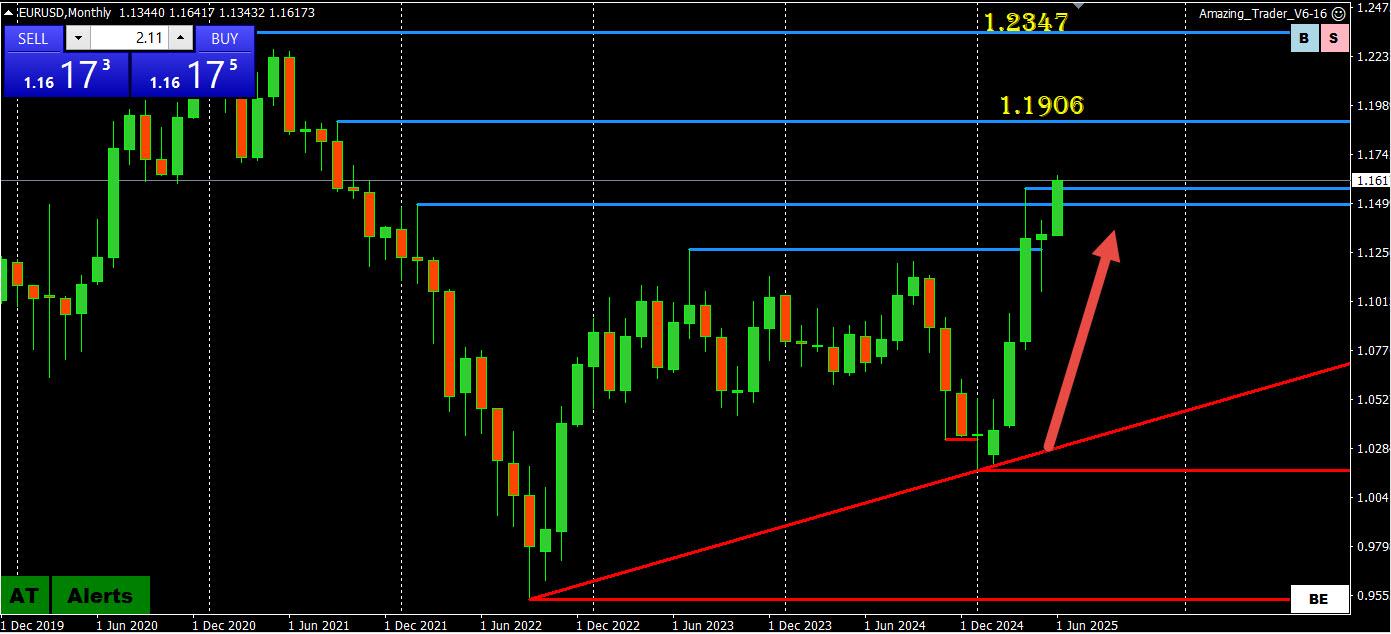
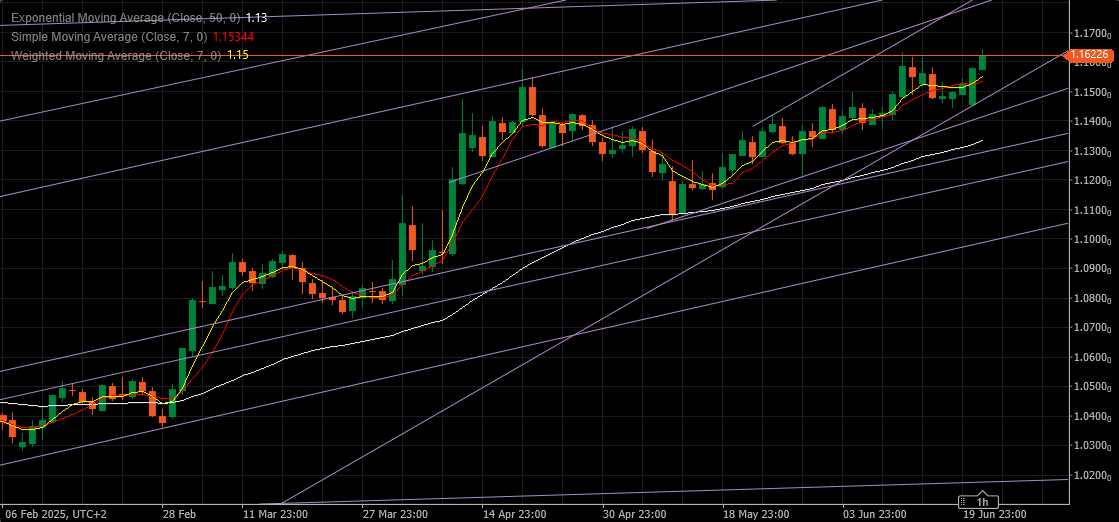
Markets taking a breather after a hectic start to the week that saw EURUSD and GBPUSD briefly trade to new 2025 highs yesterday
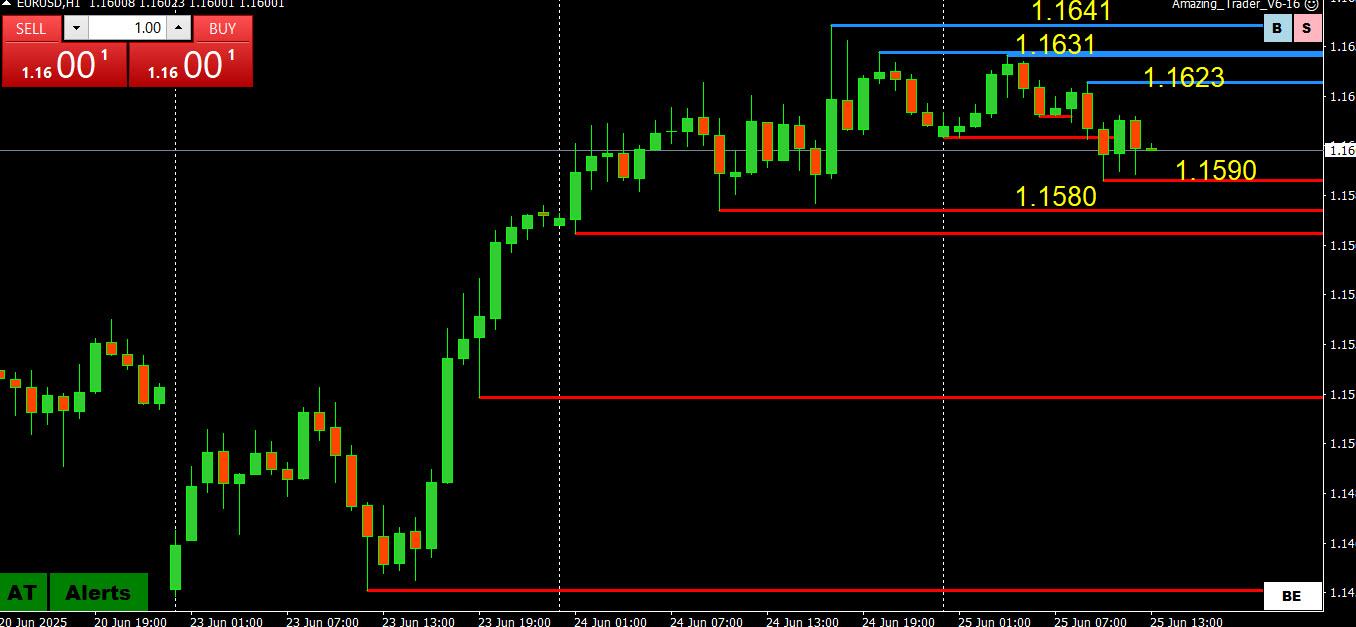
JPY is weaker across-the-board, most notably vs the USD, AUD and NZD… EURUSD is consolidating around 1.16, GBPUSD holding above 1.36
Gold is marginally firmer after a bounce from above key support yesterday
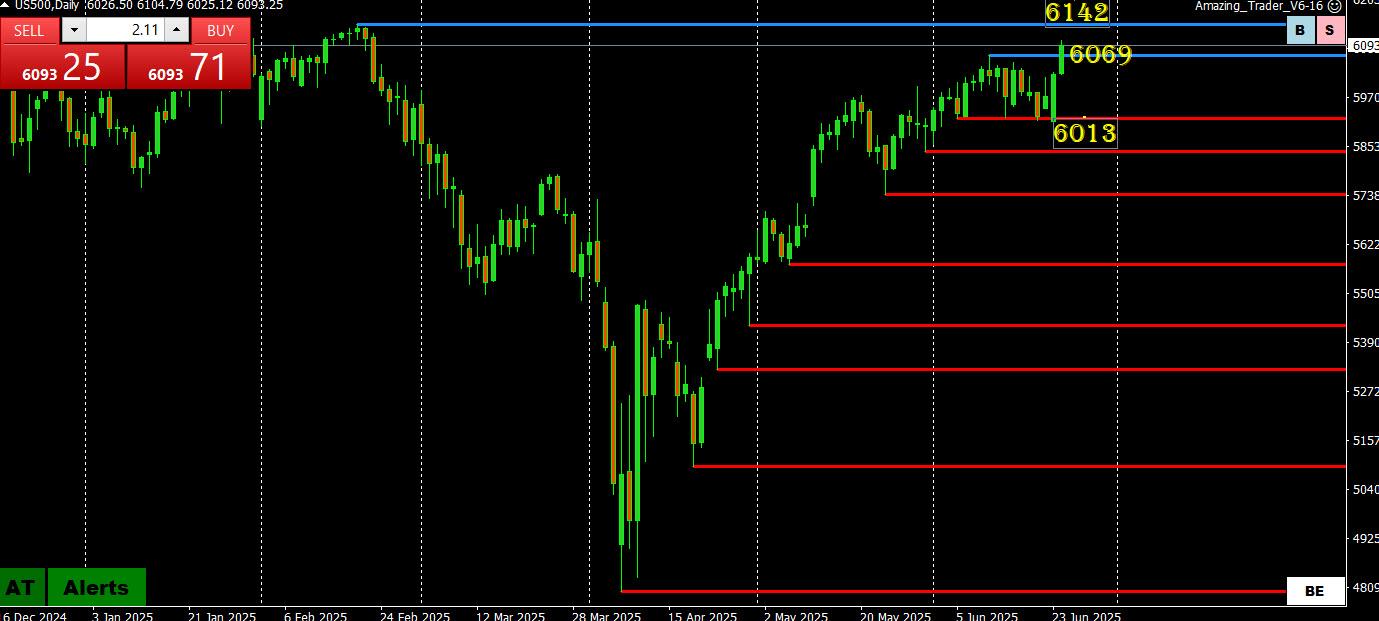
US stocks are holding steady.
Quiet economic calendar today
 June 25, 2025 at 12:14 am #26703June 24, 2025 at 8:26 pm #26702June 24, 2025 at 8:23 pm #26701June 24, 2025 at 7:29 pm #26700June 24, 2025 at 6:42 pm #26699June 24, 2025 at 6:39 pm #26698June 24, 2025 at 5:35 pm #26697June 24, 2025 at 4:37 pm #26696June 24, 2025 at 4:31 pm #26695
What’s Hot and What’s Not?
What’s Hot?
All currencies but the USD with JPY (and GBP) in the lead. New 2025 highs in EURUSD and GBPUSD but then backing off.
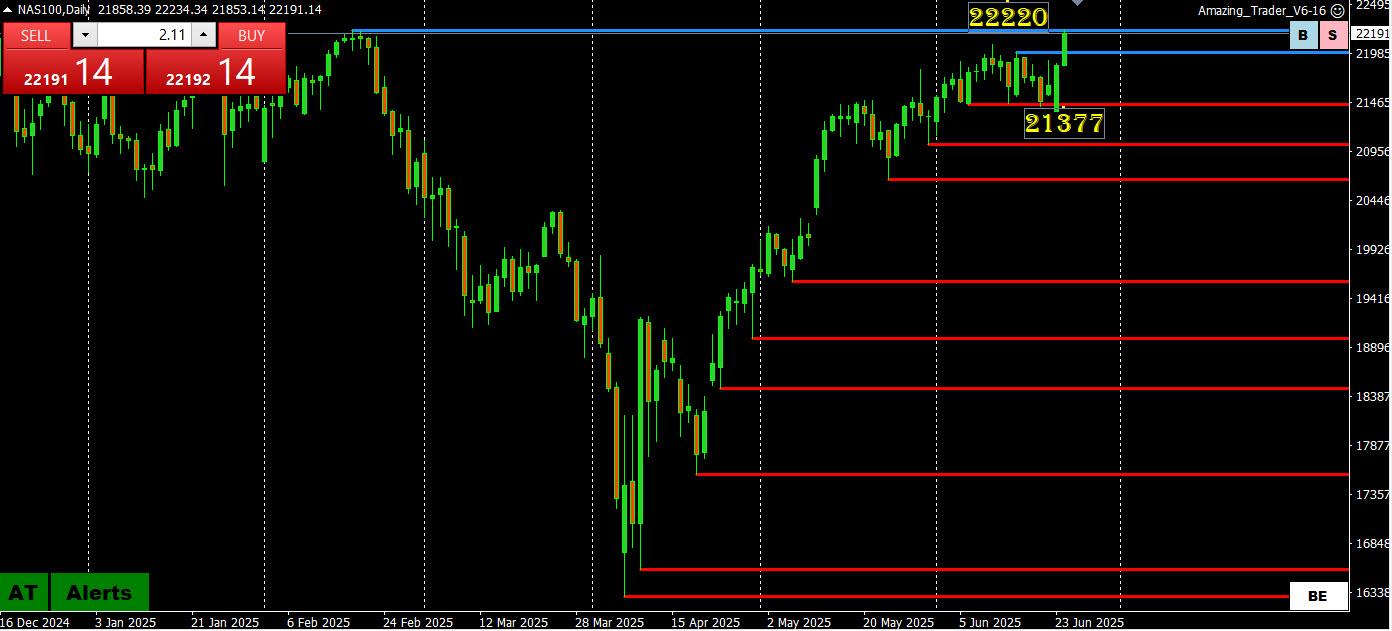
US stocks led by the NAS with NAS100 coming close to its record 22220 high.
US bonds Yields (lower modestly)
What’s Not?
The dollar extended yesterday’s reversal.
Crude oil extended yesterday’s reversal
XAUUSD broke 3338-40 support but the pause just above our key 3293 support has seen a modest bounce.
 June 24, 2025 at 4:02 pm #26694
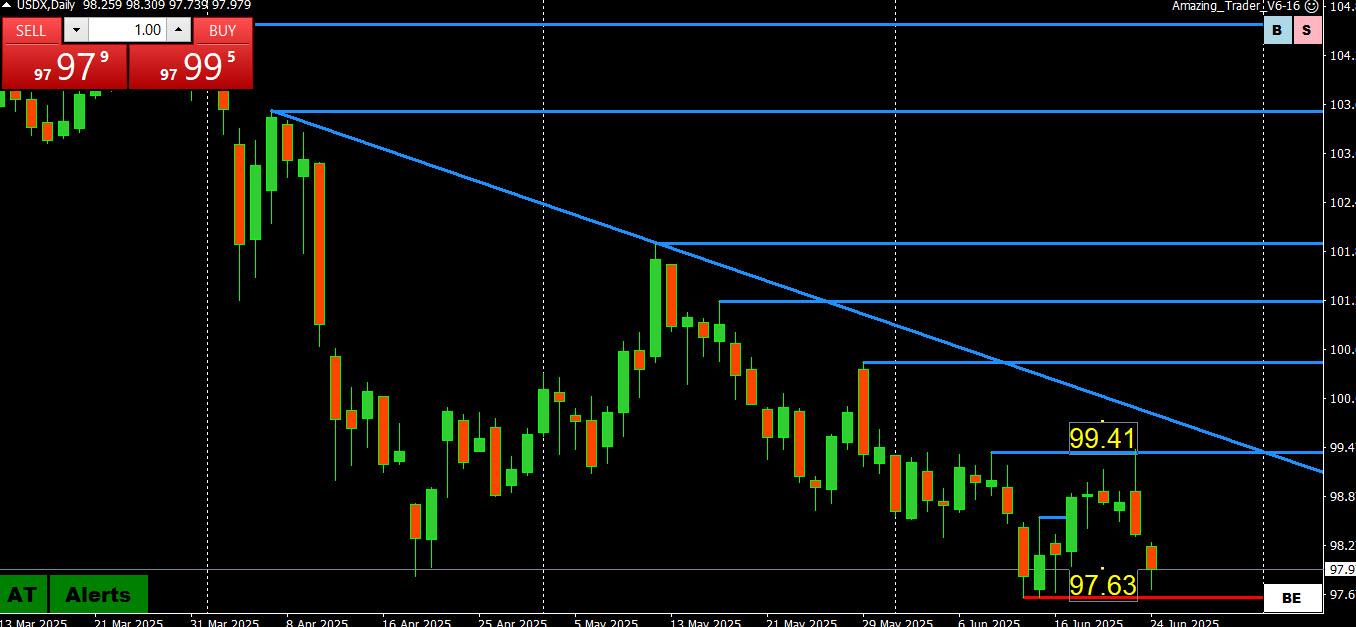
USDX (US DOLLAR INDEX)
Divergence?
Having held resistance a 99,41, USDX made a run its 2025 low at 97.63 but paused above it.
This creates some divergence with EURUSD, which briefly broke its 2025 high at 1.1631 (high 1.1641) but backed off without USDX confirmation.
With EURO representing 57.6% of USDX, the index is often used as a proxy for the EURUSD.
USDX DAILY CHART
 June 24, 2025 at 2:29 pm #26693June 24, 2025 at 2:24 pm #26692June 24, 2025 at 2:15 pm #26691June 24, 2025 at 12:34 pm #26690June 24, 2025 at 12:31 pm #26689June 24, 2025 at 12:29 pm #26688June 24, 2025 at 12:28 pm #26687June 24, 2025 at 12:26 pm #26686June 24, 2025 at 12:24 pm #26685June 24, 2025 at 12:21 pm #26684June 24, 2025 at 11:56 am #26683June 24, 2025 at 11:37 am #26682
Barclays Keeps Slightly Bearish View on Yen
Barclays retains its slightly bearish view on the yen, two strategists write in a research report. There is scope for the U.S. dollar to strengthen further against the yen than previously projected due to factors such as a reduction in U.S.-China tariff levels and a delayed U.S.-Japan policy rate convergence, they say. The yen is also likely to continue facing structural downward pressures from catalysts including continued outward investment, the strategists add. However, Barclays sees some risk of near-term yen strength that could stem from an increase in global equity risk premium due to trade uncertainty, a U.S. slowdown or geopolitical tensions. USD/JPY is 0.5% lower at 145.41.
 June 24, 2025 at 11:33 am #26681
SocGen’s Overnight Economic News Summary
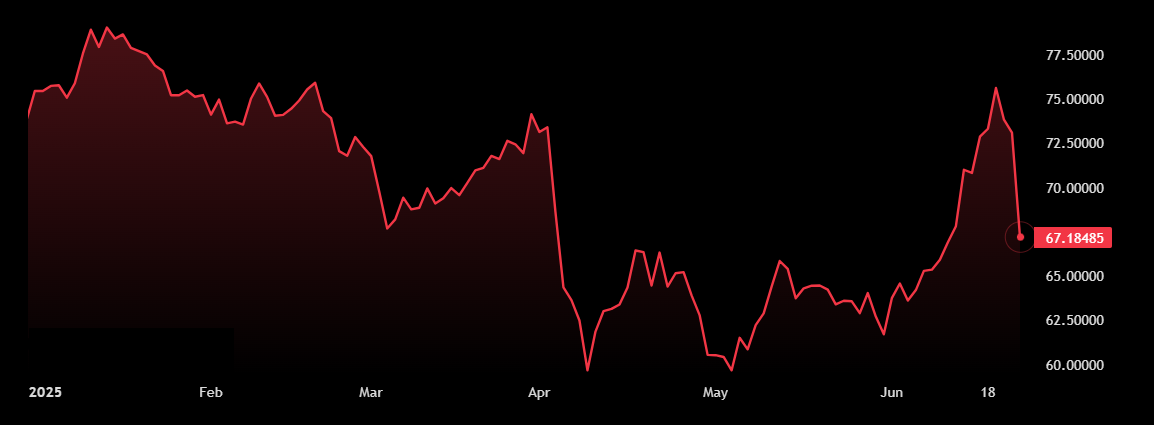
— Risk on, oil swoons 16% from peak of Monday after President Trump announces ceasefire between Israel and Iran. Netanyahu: Israel achieved war goals, agreed to Iran ceasefire. Euro Stoxx futures +1.9%. Bund unchanged at 2.51%. USDEUR reclaims 1.16. Australia’s AUD and New Zealand’s NZD lead G10 currency gains, Asia on top in emerging markets. Two-year United States Treasury on trend support at 3.80%.
— FOMC’s Bowman (voter): I would support lowering the policy rate as soon as our next meeting should inflation pressures remain contained, inflation appears to be on a sustained path toward 2%, only minimal impacts on overall core PCE inflation from changes to trade policy.
— Day ahead: Federal Reserve Chair Powell semi-annual testimony, two-year UST auction, consumer confidence, Q1 current act. Germany Ifo survey. European Central Bank speakers Lagarde, de Guindos, Lane, Kazimir. Bank of England’s Bailey, Greene, Ramsden, Pill, Breeden. Canada’s consumer price index. Hungary’s central bank (MNB) forecast on hold.
— CFTC weekly positioning: long euro raised to 13.4% OI, long yen upped to 41.2%, long sterling steady at 24.2%, short Canadian dollar (CAD or loonie) cut to 22.5%, AUD shorts raised to 47.1%, short Swiss franc rose to 29.8% and long Mexican peso increase to 37.3%.
— Nikkei +1.1%, EUR 10-year IRS unchanged at 2.52%, Brent crude -4.3% at $68.4/barrel, Gold -2% at $3,321/oz.
Crude Oil Chart
 June 24, 2025 at 10:56 am #26680
-
AuthorPosts


- You must be logged in to reply to this topic.
Search
© 2024 Global View