
- This topic has 27,906 replies, 54 voices, and was last updated 8 hours, 20 minutes ago by GVI Forex 2.
-
AuthorPosts
-
August 19, 2025 at 12:48 am #29227
Ethereum Lost 2.95% to $4337.97
Ethereum is down $132.01 today or 2.95% to $4337.97
• Largest percentage decrease since Aug. 14, 2025, when it dropped 3.92%
• Snaps a two day winning streak
• Up 16.13% month-to-date
• Up 29.7% year-to-date
• Down 10.85% from its all-time intraday high of $4865.81 on Nov. 10, 2021
• Up 65.83% from 52 weeks ago (Aug. 19, 2024), when it traded at $2615.95
• Down 9.44% from its 52-week intraday high of $4790.13 on Aug. 14, 2025
• Up 204.70% from its 52-week intraday low of $1387.85 on April 9, 2025
• Traded as low as $4228.80
• Down 5.40% at today’s intraday low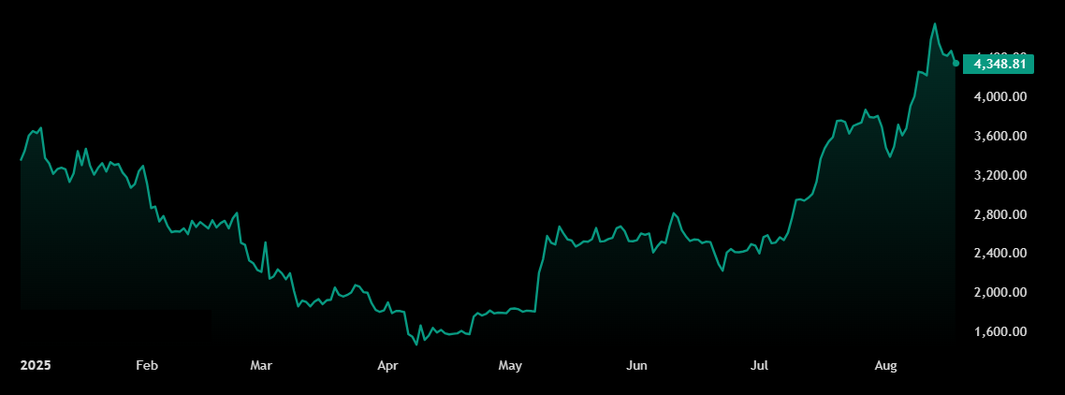 August 18, 2025 at 11:26 pm #29226
Dollar Supported by Higher T-Note Yields
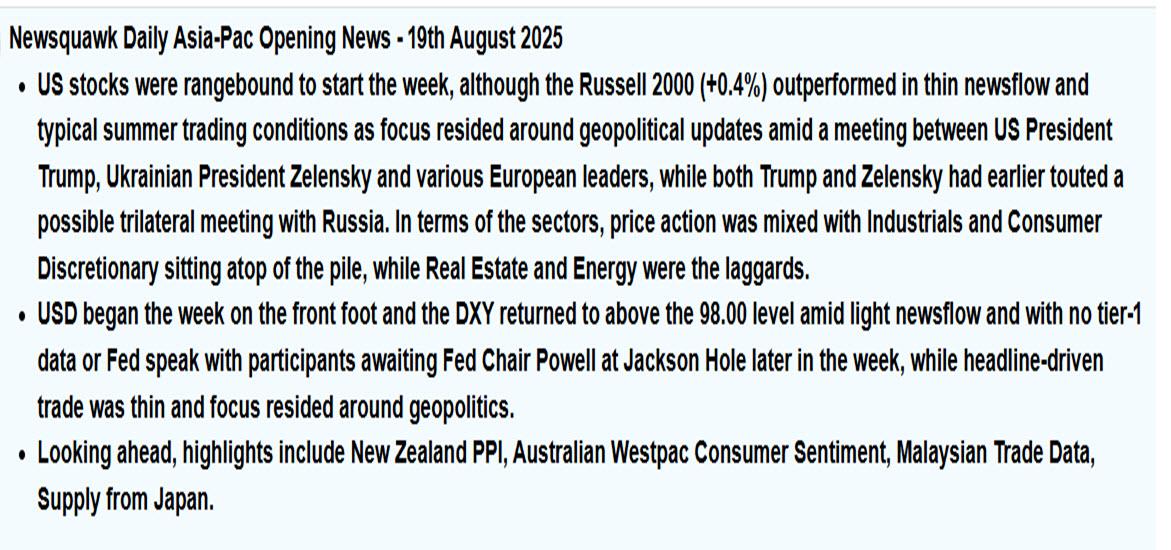
The dollar index DXY on Monday rose by +0.30%. The dollar moved higher Monday on carryover support on concern that last week’s CPI and PPI reports showed an acceleration of prices that could keep the Fed from cutting interest rates at next month’s FOMC meeting.
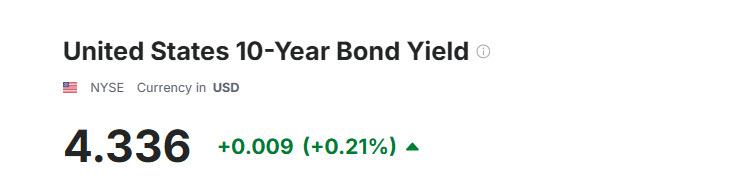
The reduced chances of a Fed rate cut pushed the 10-year T-note yield up to a 2-week high on Monday at 4.35%. Gains in the dollar were limited after Monday’s news showed the Aug NAHB housing market index unexpectedly declined.
The US Aug NAHB housing market index unexpectedly fell -1 to 32, weaker than expectations of an increase to 34.
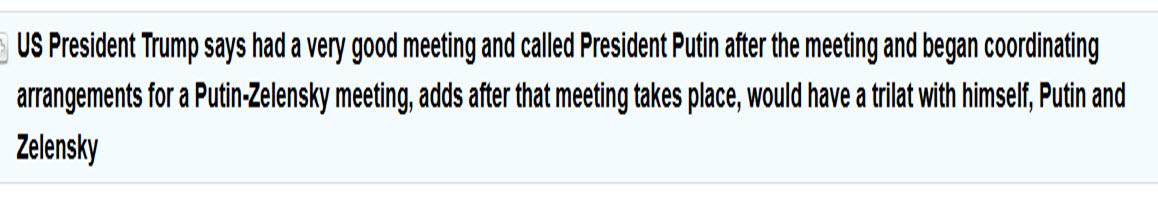
Gains in the dollar were limited due to underlying foreign investor concern about the possibility of a politically-driven US monetary policy, following US Treasury Secretary Bessent’s appearance last Wednesday, which seemed to give the Fed marching orders on how much to cut interest rates. The markets are awaiting the outcome of today’s meeting between President Trump and European leaders on any progress toward ending the Russian-Ukrainian war.
The outcome could have macroeconomic implications regarding tariffs and oil prices, and could, of course, have significant consequences for European security.
The markets continue to adjust to the inflation outlook following Thursday’s hawkish PPI report. Following the report, the markets erased any hopes of a -50 bp rate cut at the Fed’s September meeting and pulled back expectations for a -25 bp rate cut to 84% area from 93% before the report.
Federal funds futures prices are discounting the chances for a -25 bp rate cut at 84% at the September 16-17 FOMC meeting and at 51% for a second -25 bp rate cut at the following meeting on October 28-29. EUR/USD Monday rose by +0.47% due to strength in the dollar. The yen also continues to be undercut by concern that US tariff policies will harm the Japanese economy.
On the positive side for the yen was Monday’s news that showed the Japanese Jun tertiary index rose more than expected. The Japan Jun tertiary index rose +0.5% m/m, stronger than expectations of +0.2% m/m. December gold (GCZ25) on Monday closed down -4.60 (-0.14%), and September silver (SIU25) closed up +0.054 (+0.14%).
Precious metal prices on Monday settled mixed, with gold prices falling to a 2-week low. Strength in the dollar on Monday was bearish for metals. Also, higher T-note yield undercut gold prices after the 10-year T-note yield climbed to a 2-week high on Monday at 4.35%.
Gold prices are also under pressure due to reduced chances for a Fed rate cut at next month’s FOMC meeting, following a bearish July PPI report last Thursday that knocked the chance of a Fed rate cut down to 84% from 93% before the report.
Gold continues to have safe-haven support related to US tariffs and geopolitical risks, including the conflicts in Ukraine and the Middle East. Fund buying of precious metals continues to support prices after gold holdings in ETFs rose to a 2-year high last Friday, and silver holdings in ETFs reached a 3-year high last Thursday.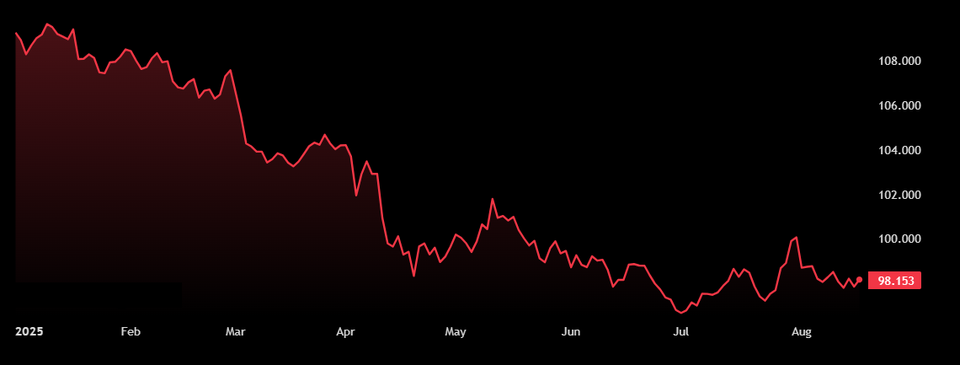 August 18, 2025 at 10:13 pm #29224
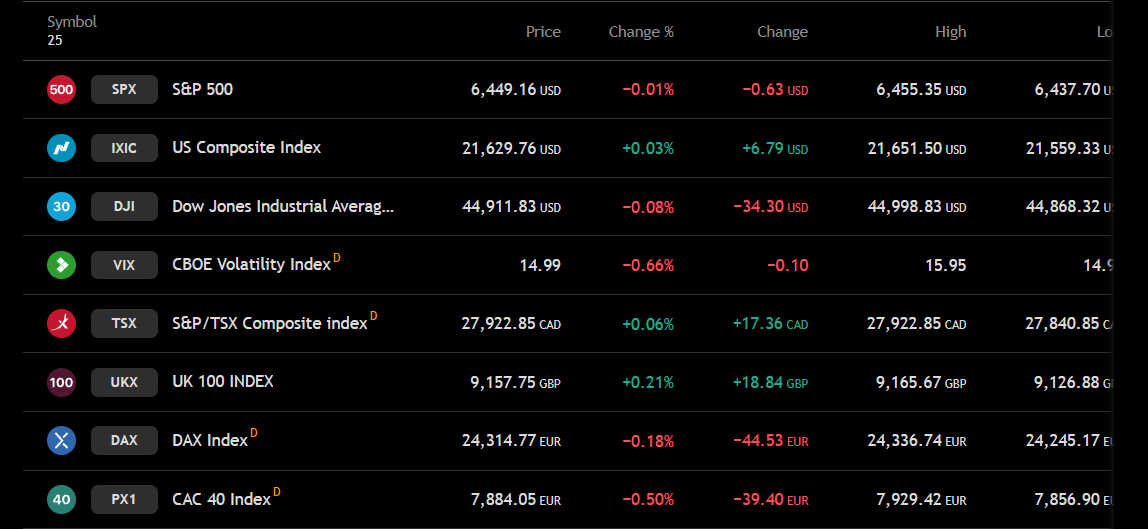
TSX Edges Higher on Monday
The S&P/TSX edged up to close at 27,923 on Monday as investors avoided large directional bets ahead of Tuesday’s Canadian CPI release and the Jackson Hole symposium starting Friday.
Markets are focused on Fed Chair Jerome Powell’s remarks and the Fed minutes as odds of a September cut have risen, while the domestic inflation print will be parsed for clues that could alter the Bank of Canada’s policy path.
Geopolitically President Trump signalled that Ukraine should abandon hopes of reclaiming annexed Crimea or joining NATO, a stance that aligns him more with Moscow’s approach to a negotiated settlement. On the sector level Shopify rose 1.1%, Thomson Reuters added 0.9% and Manulife gained 0.7% to lead gains, while gold-related names Wheaton Precious and Franco-Nevada slipped more than 0.7% and heavyweight Canadian Pacific Railway fell 0.9%.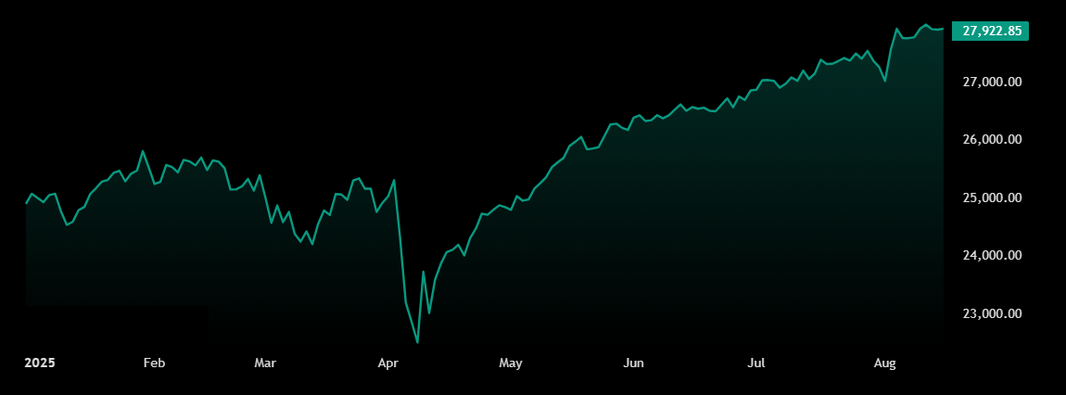 August 18, 2025 at 10:13 pm #29221August 18, 2025 at 10:00 pm #29217August 18, 2025 at 9:10 pm #29215August 18, 2025 at 9:10 pm #29216August 18, 2025 at 8:40 pm #29214August 18, 2025 at 8:37 pm #29213August 18, 2025 at 8:33 pm #29212August 18, 2025 at 8:24 pm #29211
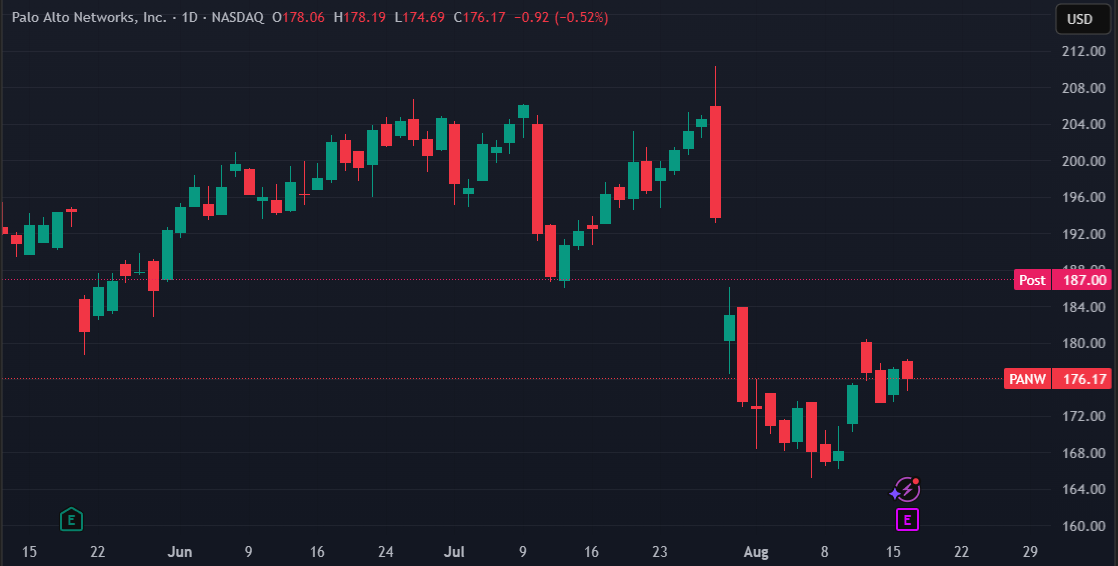
Palo Alto Networks Inc. – PANW
BRIEF-Palo Alto Networks Q4 EPS USD 0.36
Palo Alto Networks Q4 pretax profit USD 591.8 million.
· Q4 operating income USD 497.2 million
· Q4 revenue USD 2,536.3 million vs. IBES estimate USD 2,502 million
· Q4 adjusted EPS USD 0.36 vs. IBES estimate USD 0.88
· Q4 net income USD 253.8 million
· outlook Q1 revenue USD 2,450-2,470 million
· outlook FY revenue USD 10,475-10,525 million
· outlook Q1 revenue growth 15%
· outlook FY revenue growth 14%
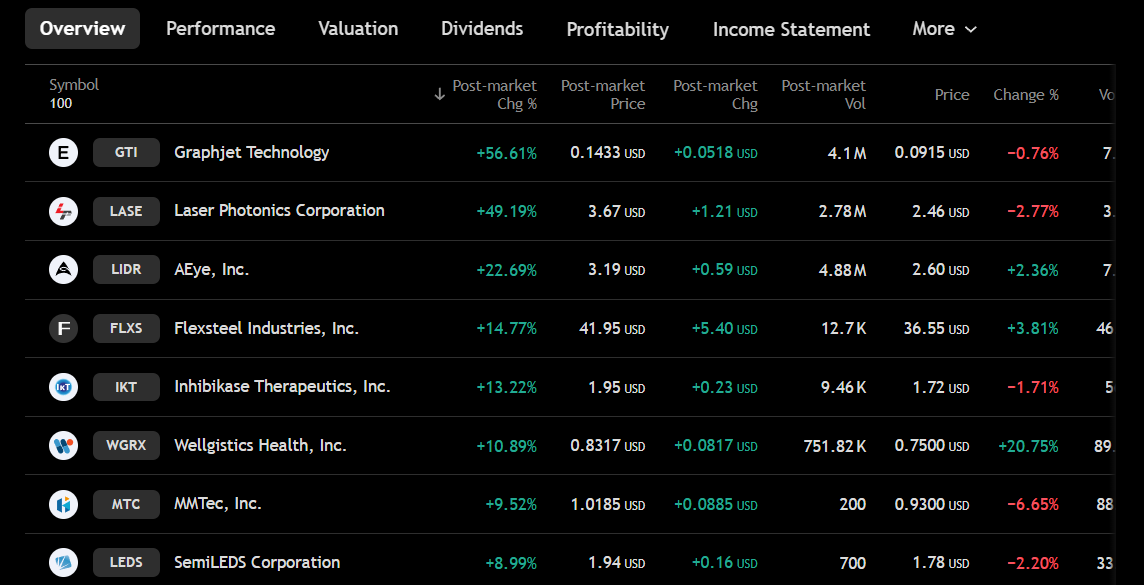
PANW closed at 176.17 – Post Market 187.00
 August 18, 2025 at 8:07 pm #29210August 18, 2025 at 8:01 pm #29209August 18, 2025 at 7:27 pm #29208August 18, 2025 at 6:58 pm #29207August 18, 2025 at 5:48 pm #29203August 18, 2025 at 5:12 pm #29199August 18, 2025 at 5:05 pm #29198August 18, 2025 at 5:01 pm #29197August 18, 2025 at 4:53 pm #29196August 18, 2025 at 4:48 pm #29195
Intel Corporation – INTC
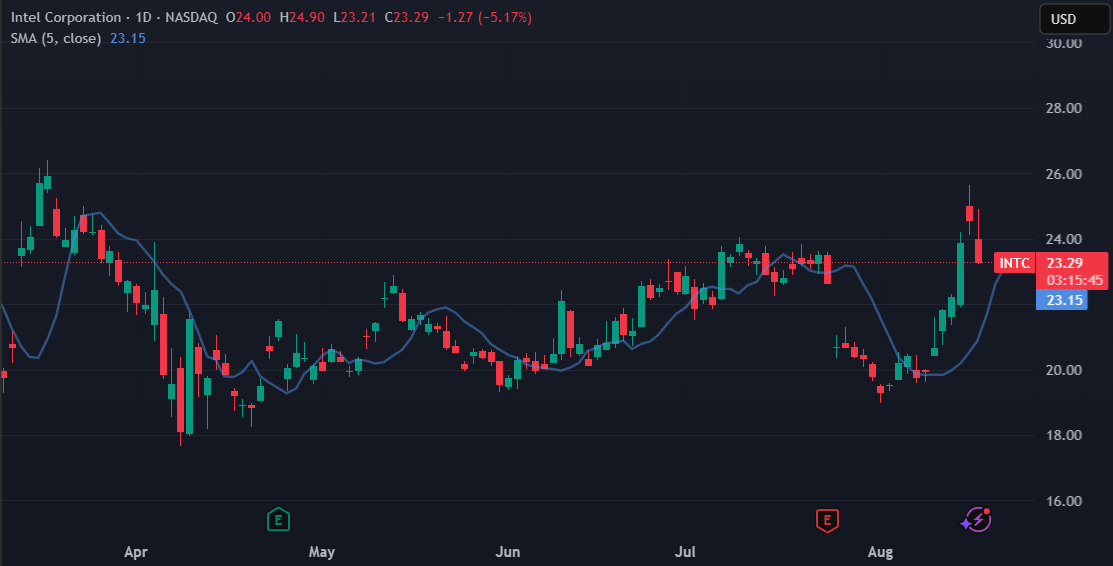
Trump administration said to discuss taking 10% in Intel, Bloomberg News reports
The Trump administration is said to discuss taking a 10% stake in American chipmaker Intel INTC, Bloomberg News reported on Monday, citing a White House official and other people familiar with the matter.
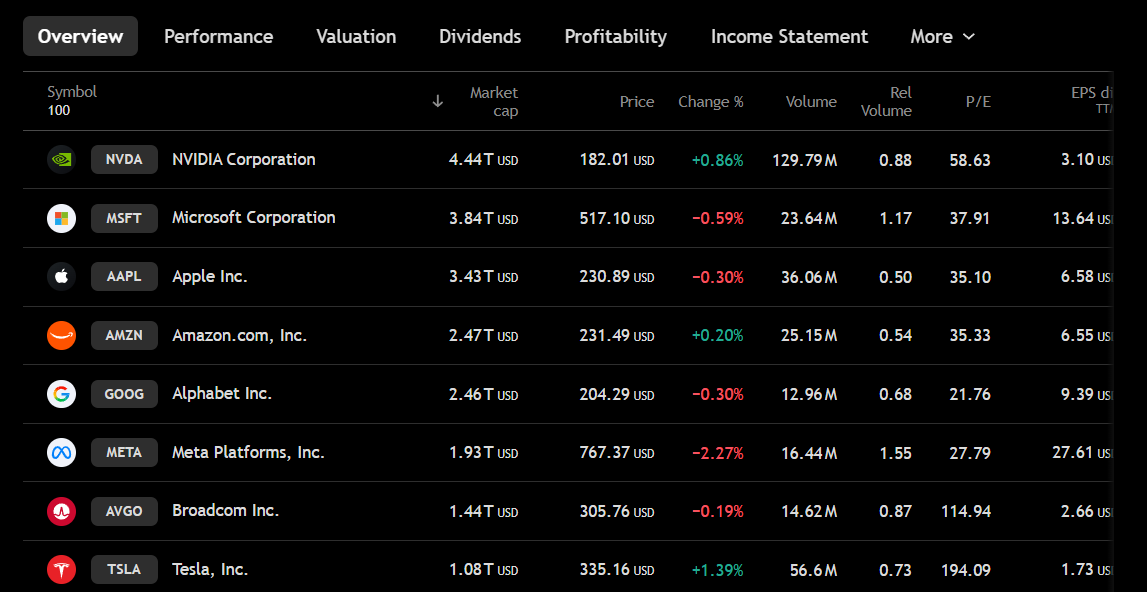
Shares of the company were down 3.8%.
The federal government is considering a potential investment in Intel that would involve converting some or all of the company’s grants from the U.S. Chips and Science Act into equity, the report said.
Trump, who met Intel CEO Lip-Bu Tan on August 11, has taken an unprecedented approach to national security.
He has pushed for multibillion-dollar government tie-ups in semiconductors and rare earths such as a pay-for-play deal with Nvidia NVDA and an arrangement with rare earth producer MP Materials MP to secure critical minerals.
Federal backing could give Intel more breathing room to revive its loss-making foundry business, analysts said, but it still suffers from a weak product roadmap and challenges in attracting customers to its new factories.
 August 18, 2025 at 4:41 pm #29194August 18, 2025 at 4:41 pm #29193
SOLUSD – Solana
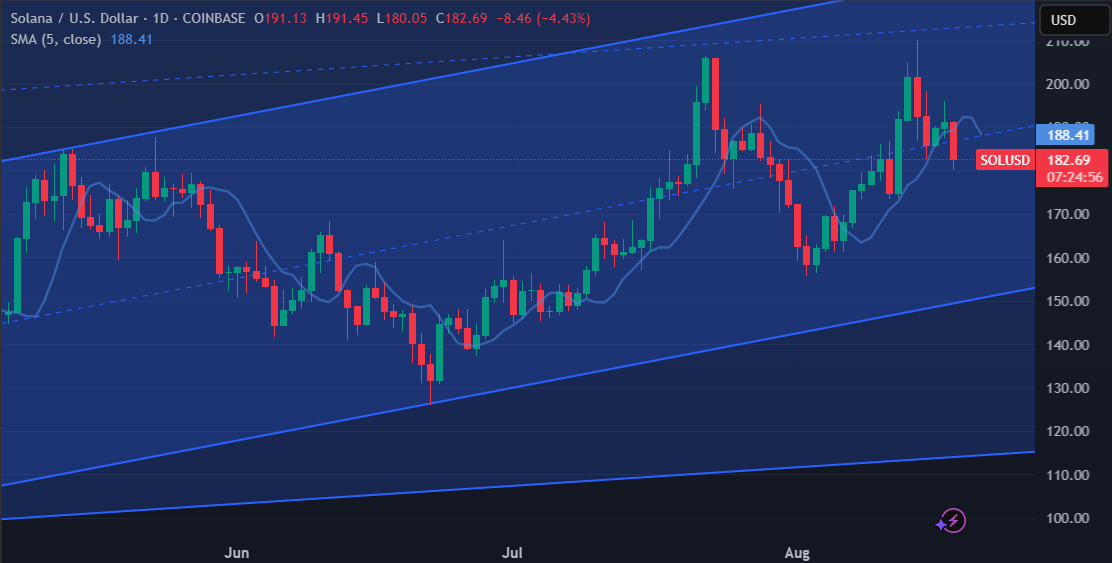
Same as BTC and ETH Solana took a dive today.
So they all decided to move in unison…
Resistances: 191.45, 192.45 & 195.90
Supports: 180.05, 173.45 & 155.75
As long as it holds above 170.85 Solana can go back in being Bullish.
For that to happen , it also has to go above 191.45 this week…
 August 18, 2025 at 4:04 pm #29192August 18, 2025 at 3:53 pm #29191August 18, 2025 at 3:21 pm #29190
What’s hot and what’s not?
What’s hot?
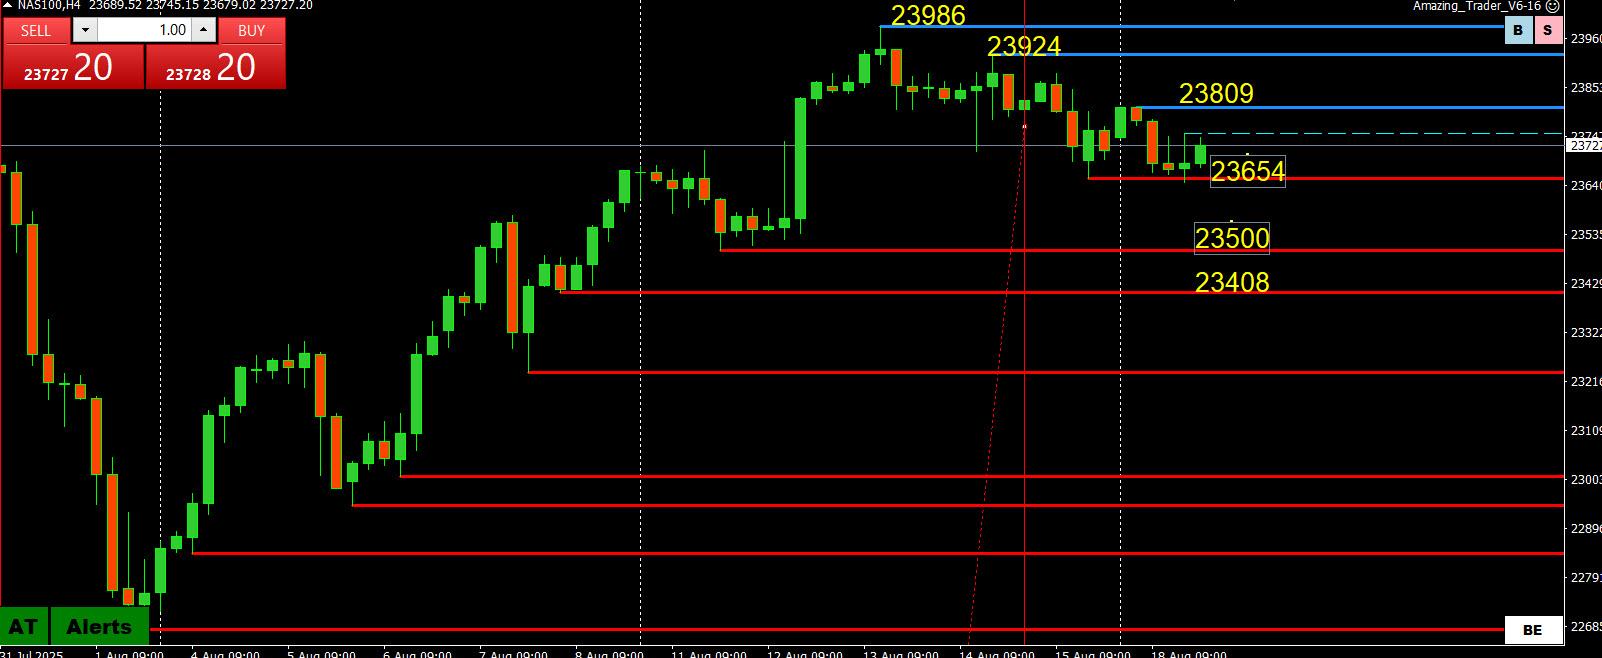
The dollar is up ahead of the Trump-Zelensky/European leaders meeting
What’s not?
Low expectations for the Trump-Zelensky meeting
All currencies but the USD
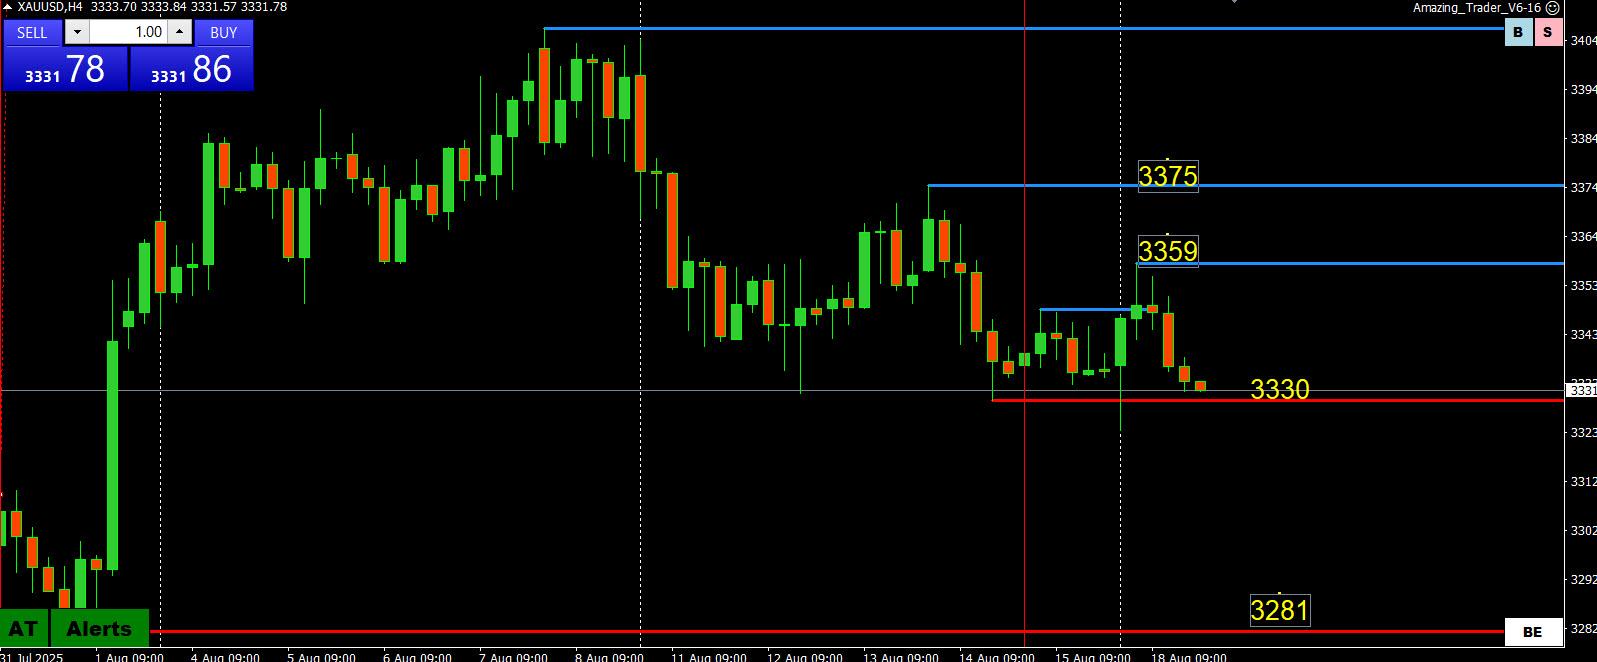
GOLD is steady on the day but off earlier high
US bonds (yields up on the day after trading softer early on… 10 year extending yield high to 4.345%)
BITCOIN is lower
What’s hot/not?
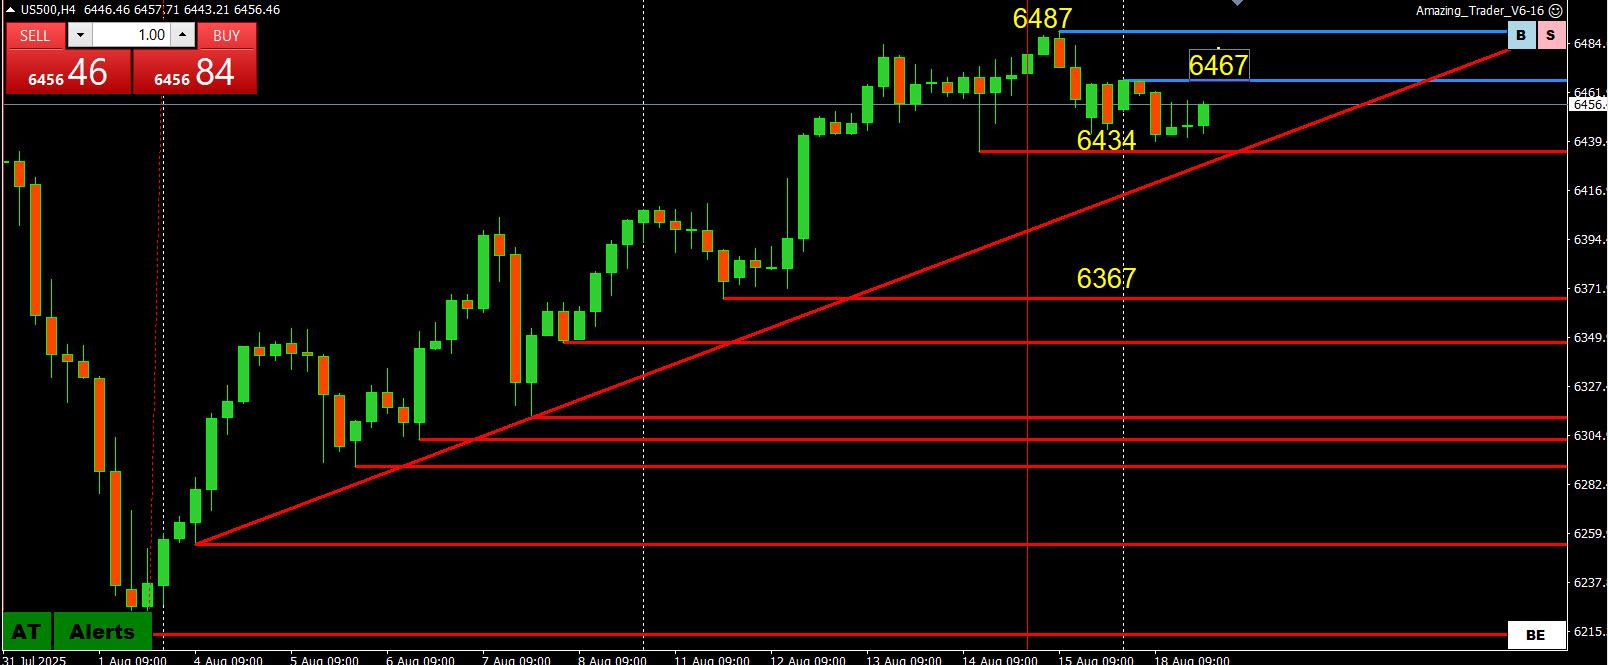
US stocks are steady awaiting the Trump-Zelensky/Europe meeting August 18, 2025 at 3:01 pm #29189
ETHUSD – Ethereum
Ether went yesterday above that 4510.00 level, but failed to close above it.
As I said last night : If below on close tonight ( 4510.00 )– Monday might bring a sharp move down
And what a down move that was….
Now unless some unseen force provides a great support and rebound ETH back up ( doubt that 😀 , Ether is destined to check on supports at:
3955.00 & 3685.00
Resistances: 4165.00 & 3940.00
Intraday pressure : Up
 August 18, 2025 at 2:57 pm #29188August 18, 2025 at 2:54 pm #29187August 18, 2025 at 2:53 pm #29186
BTCUSD – Bitcoin
BTC lost Uptrend support at 116.300 an now what’s left is another one at 114.700
Pass that one and we are on the way to 110.820 – last chance to rebuild the Bullish mojo and continue Up.
As you can see from this chart, that last support is a horizontal one – separates Bitcoin from falling back to 97.500 and consequently even 90.335
Intraday pressure : Down

-
AuthorPosts


- You must be logged in to reply to this topic.
Search
© 2024 Global View