
- This topic has 27,673 replies, 54 voices, and was last updated 11 hours, 44 minutes ago by GVI Forex 2.
-
AuthorPosts
-
November 18, 2024 at 2:25 pm #14533November 18, 2024 at 1:44 pm #14532November 18, 2024 at 1:08 pm #14531November 18, 2024 at 12:15 pm #14530November 18, 2024 at 11:53 am #14529November 18, 2024 at 11:49 am #14528
A look at the day ahead in U.S. and global markets from Mike Dolan
Wall Street feels a little bruised after its worst week in 10 spoiled the post-election party, with home truths on interest rates and earnings seeping back in along with all the uncertainty on what a new administration will actually do come January.
Stocks were side-swiped on Friday after a week of irksome inflation readings, hot retail updates and Federal Reserve boss Jerome Powell’s equivocation on future easing.
There was also trepidation, however, ahead of chip giant Nvidia (NASDAQ:NVDA) latest earnings report on Wednesday – as the world’s biggest company by market value and artificial intelligence bellwether faces another test of the near 800% stock boom over the past year.
November 18, 2024 at 11:47 am #14527NEWSSQUAWK US OPEN
US futures are mixed, Bonds edge lower whilst XAU gains; ECB Lagarde due
Good morning USA traders, hope your day is off to a great start! Here are the top 4 things you need to know for today’s market.
4 Things You Need to Know
European bourses are generally on the backfoot, US futures are mixed.
Dollar is incrementally lower, JPY underperforms after BoJ Governor Ueda continued to signal a lack of urgency to hike rates.
USTs are marginally lower whilst Bunds extend losses and slips below 132.00.
WTI & Brent are firmer in what has been a choppy session, XAU eyes USD 2.6k to the upside.
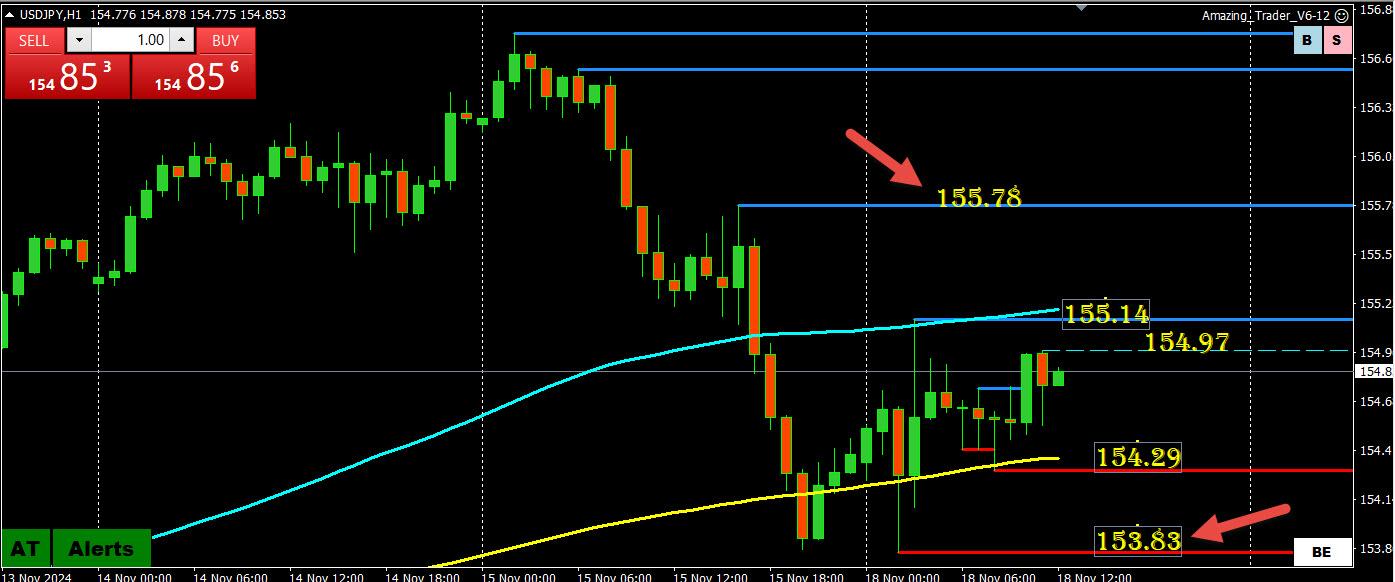
November 18, 2024 at 11:20 am #14526November 18, 2024 at 10:46 am #14525November 18, 2024 at 10:42 am #14524Thsi article is worth a read given the way USDJPY has traded the past 2 days.
When you see two currencies move in opposite directions you can affine there is a cross flow going through that the market is having trouble absorbing.
Forex Trading Confidential: What Makes USDJPY Move?
 November 18, 2024 at 10:36 am #14523
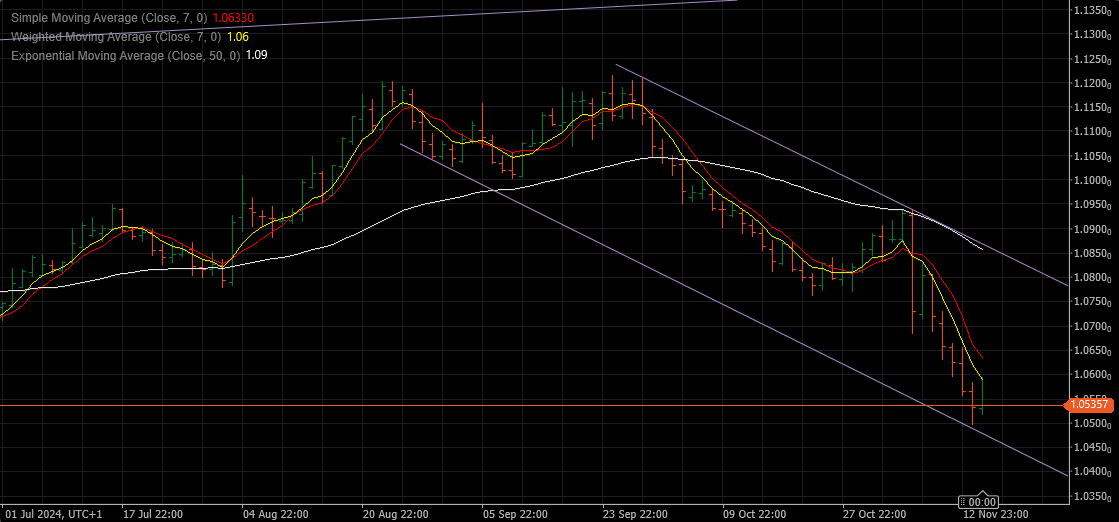
EURUSD 4 HOUR CHART – NO SURPRISE
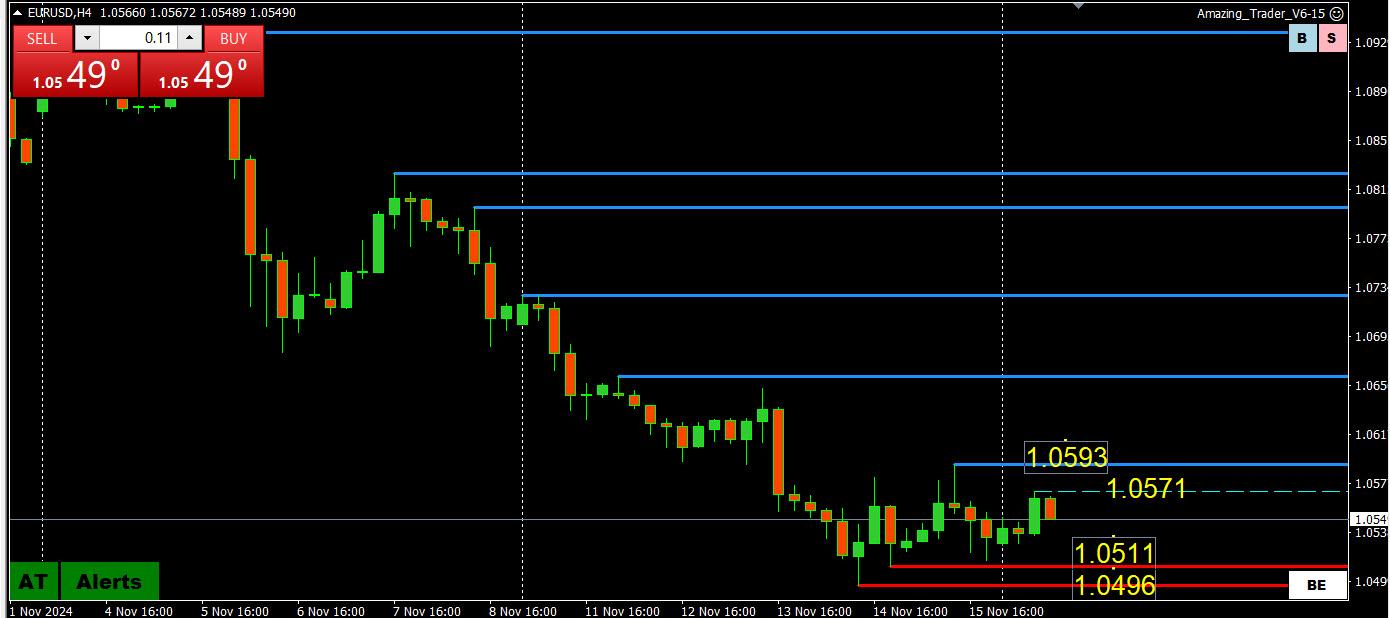
It should come as no surprise to see EURUSD gravitate back to 1.0550, which is the bias setting level while within 1.05-1.06
Note firmer EUR crosses (e.g. EURJPY, EURGBP) giving EURUSD support but not enough to break the key 1.0593 level.
So let’s call it consolidation of the downtrend where only a break of 1.0590-00 would shift the risk from 1.0495-10.
November 18, 2024 at 10:23 am #14522XAUUSD 4 HOUR CHART – Rebounding but obstacles loom
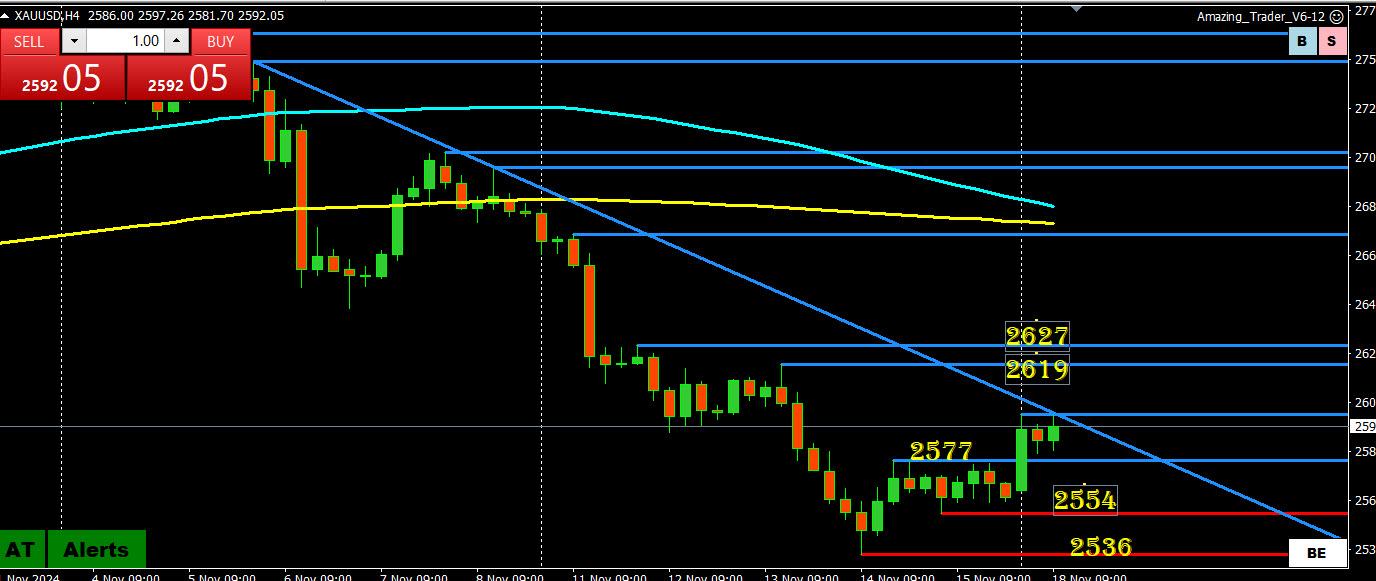
Rebound would need to regain 2600 to ease pressure on the downside but would need to break 2619 to confirm this latest episode to the downside is over.
Support starts at 2577 (former resistance) and 2554 (use 2550-55). Only below the latter would expose the 2536 low.
November 18, 2024 at 10:15 am #14521November 18, 2024 at 2:11 am #14520November 18, 2024 at 2:05 am #14519November 18, 2024 at 1:32 am #14518November 18, 2024 at 12:00 am #14517November 17, 2024 at 10:49 pm #14516November 17, 2024 at 10:40 pm #14515November 17, 2024 at 10:10 pm #14513November 17, 2024 at 9:50 pm #14511THIS WEEK’S MARKET-MOVING EVENTS (all days local)
Monday starts off with Canadian housing starts, which are expected to rise to an annual rate of 240,000 in October after bouncing back to 224,000 in September from a recent low of 213,000 in August. Housing starts have been trending down, reflecting overall weakness in Canada despite relaxed financing conditions delivered by the Bank of Canada.
On Tuesday, Canada’s annual inflation reading is expected to correct higher to 1.9 percent in October from 1.6 percent in September and 2.0 percent in August. The September figure was the lowest since February 2021. On a monthly unadjusted basis, forecasters expect a 0.3 percent rebound after the 0.4 percent drop in September and 0.2 percent decline in August. Inflation readings like this are expected to keep rate cuts coming from the Bank of Canada.
US housing starts are estimated to be a little soft at a 1.3 million unit rate in October versus 1.4 million in September. Permits are expected flat at 1.4 million versus 1.4 million in September.
Wednesday, Japan’s merchandise trade is balance is expected to post a deficit of ¥132.2 billion for a fourth consecutive shortfall, after a revised ¥294.1 billion deficit in September and compared with a ¥702.86 billion deficit in October 2023 and a record shortfall of ¥3,506.43 billion (¥3.51 trillion) in January 2023. Japanese export values are forecast to show a rebound in October, up 3.0%, after falling 1.7% in September for their first year-on-year drop in 10 months. An increase in semiconductor-producing equipment appears to be partly offset by drops in automobiles, mineral fuels and iron/steel. Import values are expected to mark their first decline in seven months, down 1.8%, on crude oil, semiconductors and smartphones, following a 2.1% rise the previous month.
China’s monetary authorities cut the loan prime rate by 25 bp in last month’s fixing to boost the economy. Forecasters uniformly expect no change this month in 1-year or 5-year rates.
UK’s consumer price index is estimated to fall more than expected to a 1.7 percent rate in September from 2.2 percent in August. Forecasters expect the rate to rebound to 2.2 percent on year in October with a 0.5 percent jump on the month. A big rise in household energy bills is expected to push headline inflation higher in October. Core inflation is expected to be better behaved.
On Thursday, US jobless claims are expected to edge up to 219,000, closer to the four-week moving average at 227,250 after a lower than expected 217,000 in the prior week.
Friday, Japan’s consumer price index is expected to ease further to 2.2% in the core reading in October from 2.4% in September and 2.8% in August. The year-on-year increase in the total CPI is forecast at 2.3%, also down from 2.5% in September. By contrast, underlying inflation measured by the core-core CPI (excluding fresh food and energy) is seen at 2.3%, up from 2.1% the previous month, as this relatively younger series is unaffected by energy prices. The Bank of Japan, which expects inflation to be anchored around its 2% target by early 2026, is on course for at least three more 25 basis point rate hikes that would take the overnight interest rate target to 1% by late 2025 as part of its gradual normalization process after more than a decade of large-scale eas
Econoday
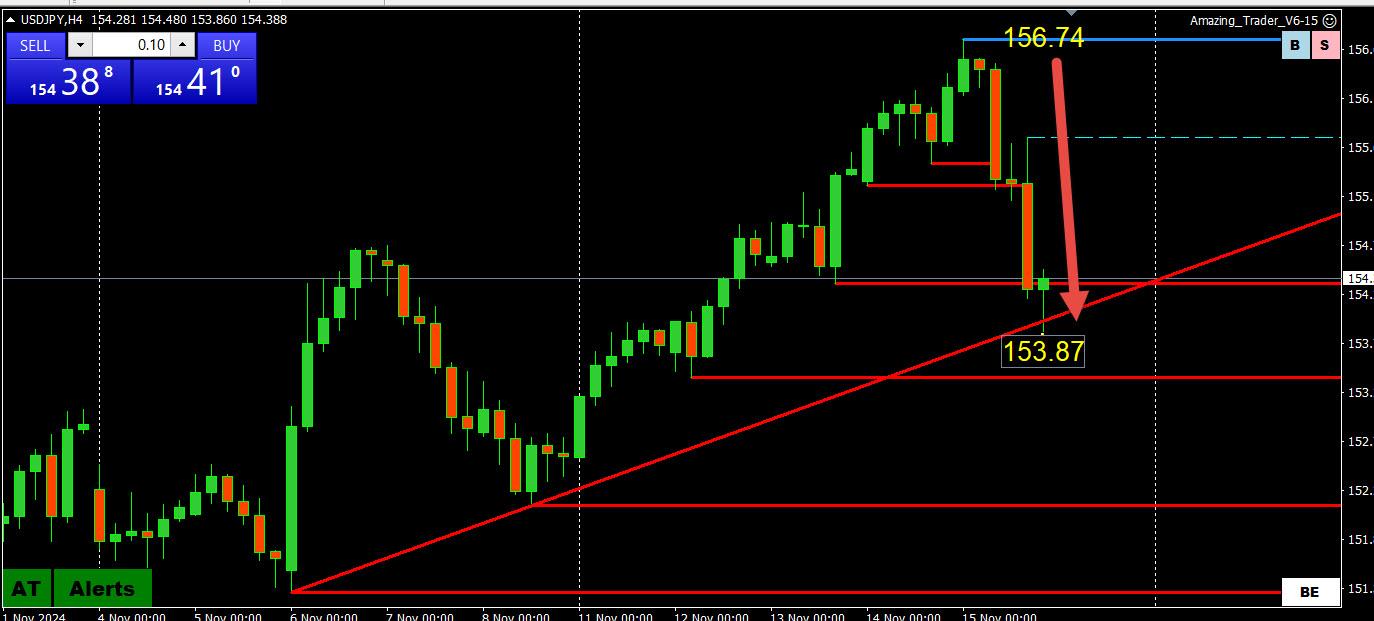
November 17, 2024 at 8:23 pm #14507USDJPY 4 HOUR CHART – DAY AFTER

Monday is like the day after an earthquake, meaning the day after the USDJPY meltdown.
Keep an eye on US stocks as Friday’ s plunge wa partly behind the hort JPY unwinding
4 HOUR CHART
:
Watch the trendline,152.14 I the key support that needs to hold to keep the focus on 155.
Back above 155 would be needed to restore a bid bias.
Logic says there should be offers above the market by those caught long.
November 17, 2024 at 7:53 pm #14506November 17, 2024 at 4:29 pm #14488November 17, 2024 at 3:23 pm #14478November 16, 2024 at 12:18 pm #14445November 16, 2024 at 12:14 pm #14443November 16, 2024 at 11:49 am #14439November 16, 2024 at 9:41 am #14437November 14, 2024 at 8:13 pm #14435 -
AuthorPosts


- You must be logged in to reply to this topic.
Search
© 2024 Global View