
- This topic has 28,268 replies, 54 voices, and was last updated 1 hour, 46 minutes ago by GVI Forex 2.
-
AuthorPosts
-
April 29, 2025 at 4:35 pm #23370April 29, 2025 at 4:31 pm #23369April 29, 2025 at 3:53 pm #23366
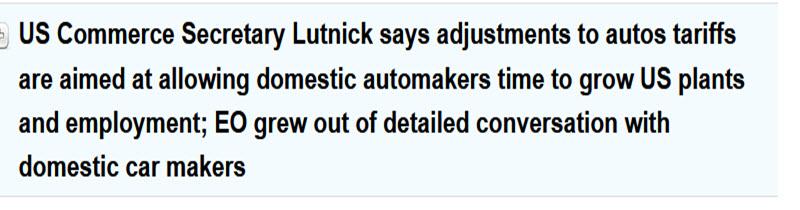
AUTO TARIFF CONCENSSIONS ARE NOT A CHANGE IN POLICY FOR FOREIGN CAR IMPORTS.
 April 29, 2025 at 3:38 pm #23365
US Stocks Gain Slight Traction
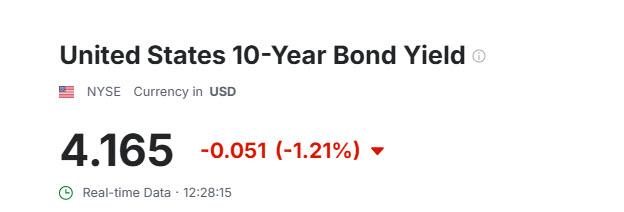
US stocks gained some traction on Tuesday, extending the period where equities track price developments in the Treasury market after pessimistic economic data and corporate signals supported wages of incoming rate cuts.
The S&P 500 and the Nasdaq were higher, and the Dow gained 200 points.
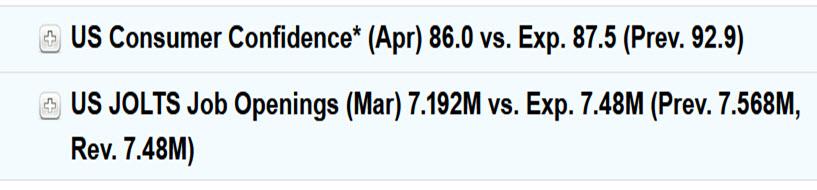
Job openings in the US were at 7.19 million in March, lower than expected, while the CB sentiment survey pointed to a surge in pessimism.
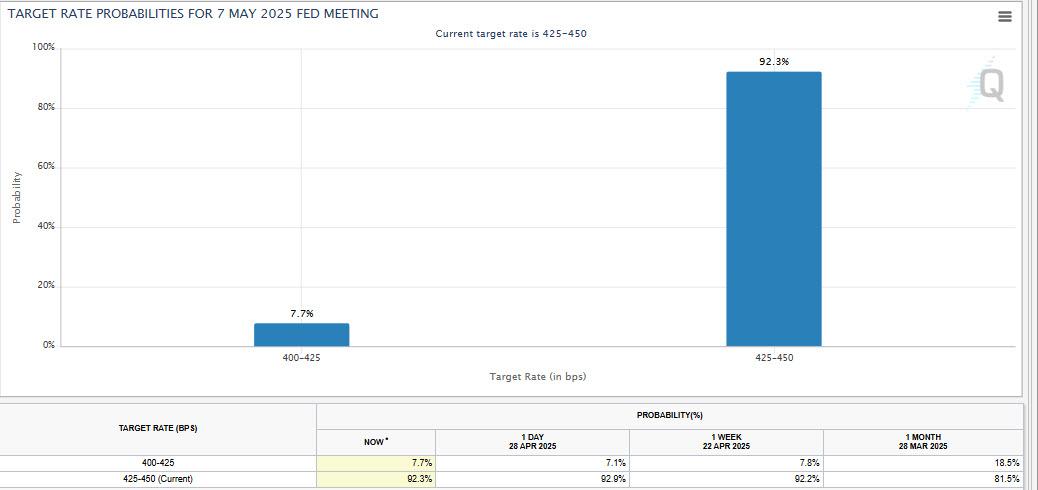
Markets moved to price 100bps in cuts by the Fed for the year, compared to the central bank’s 50bps signal last month.
Honeywell and Pfizer jumped more than 5% and 4% each on strong earnings, and software companies were higher across the board.
Still, trade and economic policy uncertainty drove UPS to refrain from giving a full-year outlook, pressuring their shares by 2%.
Also, GM sank 4% after it cancelled its share buyback and pulled its outlook due to the possibility of tariffs.
Likewise, tariff concerns drove the US to post its largest trade cap on record.
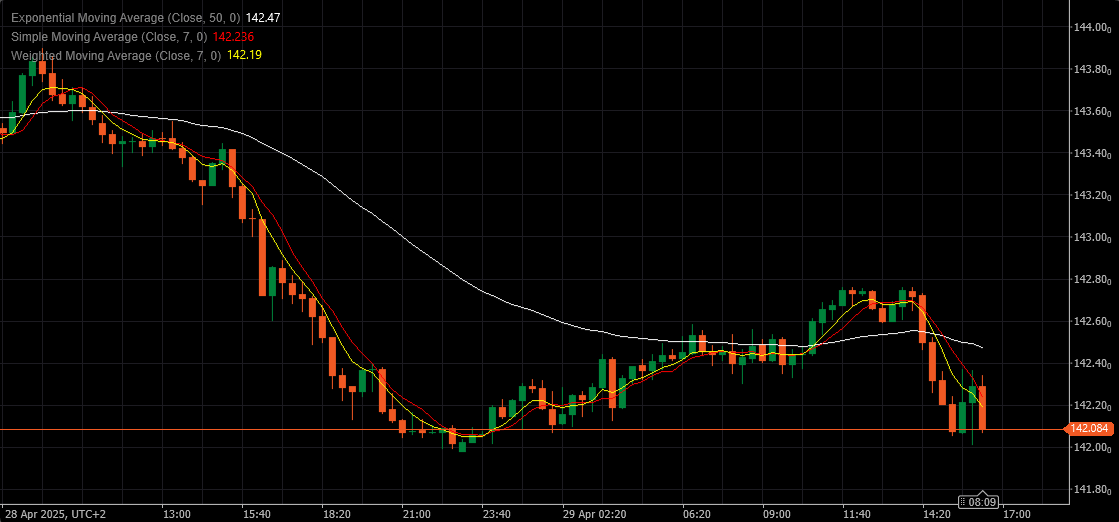
DJI Index Technicals
 April 29, 2025 at 2:55 pm #23361April 29, 2025 at 2:32 pm #23360April 29, 2025 at 2:29 pm #23359April 29, 2025 at 2:21 pm #23358
Another juicy S&P 500 target goes by the wayside as this 6,700 call is thrown into trash
HSBC slashes its S&P target to 5,600
Another one bites the dust – a Wall Street S&P 500 target, that is.
Falling in line with actions seen by other big banks this year as tariff concerns bite, HSBC on Tuesday slashed its target for the U.S. equity-market benchmark SPX to 5,600 from 6,700, based on a forecast for slower U.S. growth, sticky inflation and falling bond yields.
And they advise clients to play defence in a market that will flip-flop between recession and stagflation fears until clearer tariff and economic signals emerge.
The market will oscillate between those two scenarios till tariff turmoil eases, the Federal Reserve cuts interest rates and/or inflationary pressures don’t materialize, said Nicole Inui, HSBC’s head of equity strategy for the Americas, and analyst Preethkar R., in a note.
 April 29, 2025 at 2:14 pm #23357April 29, 2025 at 1:23 pm #23356
There was some hope Bessent would say something new but when he just said the same old stocks seemed to react back down.
Test for dollar comes next with JOLTS and Cons Conf
April 29, 2025 at 12:54 pm #23354April 29, 2025 at 12:46 pm #23352April 29, 2025 at 12:13 pm #23351DAX –Ger30
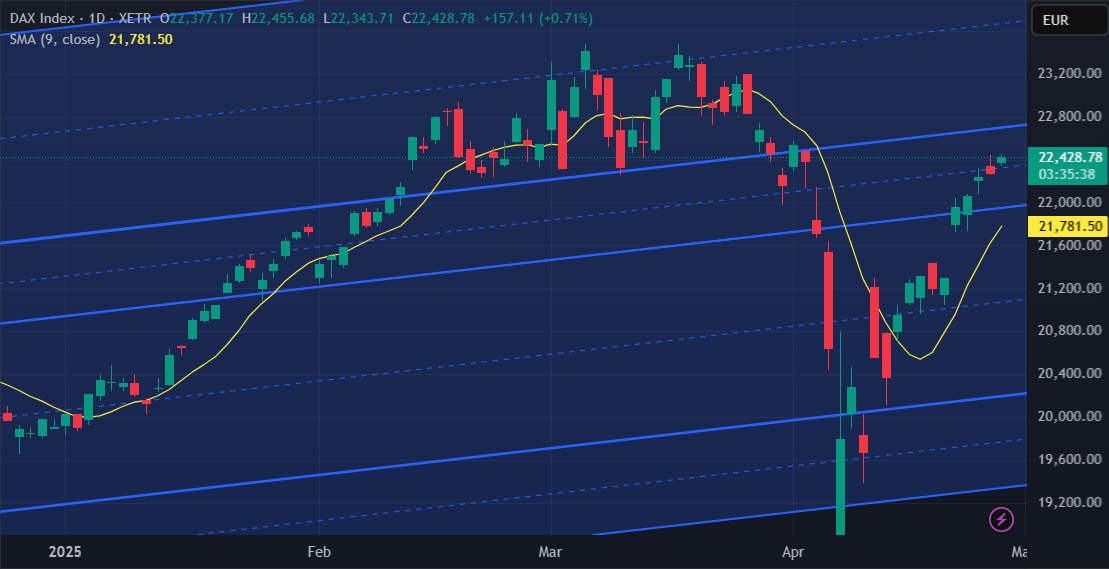
Dax going strong today so far…
Supports: 22.250, 22.050 & 21.600
Resistances: 22.500, 22.700 & 22.950
Dax has not only fully recovered from previous sharp dive to 19K , but if manages to cross above 22.700 might achieve even bigger gains then prior to the fall.
Sharp tests of supports must be watched for, but this is now Buyers heaven.
 April 29, 2025 at 12:00 pm #23350
World stocks push higher on US autos tariff relief
Key points:
· US to soften auto tariffs; US stock futures up
· Canadian dollar dips, Liberal Party wins election
· Japanese holiday thins currency trade
· Big earnings day: HSBC, General Motors report
World stocks and the dollar nudged up on Tuesday after U.S. President Donald Trump’s administration said it planned to reduce the impact of auto tariffs, a further sign of flexibility on a trade policy that has wreaked havoc on markets in April.
Market focus also turned to early signs of the impact tariff pain is having in terms of economic data and the latest company earnings.
Ahead of the Wall Street open, which stock futures suggested would be firmer, General Motors GM pulled its forecast for the year, reflecting the uncertain effects of Trump’s trade war on the industry, even as it reported strong quarterly results.
Canada’s dollar dipped against a broadly-firm U.S. currency as Canadian Prime Minister Mark Carney’s Liberals retained power in Monday’s election, but fell short of the majority government he had wanted to help him negotiate tariffs with Trump.
Sentiment across stock markets was generally positive after the U.S. said it would move to reduce the impact of duties imposed on foreign parts in domestically manufactured cars, and keep tariffs on vehicles made abroad from stacking up on other duties.
April 29, 2025 at 11:57 am #23349Dollar on track for biggest two-month fall in more than two decades
Key points:· Dollar still weak as investors fret over Sino-U.S. trade war
· Trump set to reduce the impact of automotive tariffs
· Yen to gain from widening rate gap as central banks cut
The dollar edged up on Tuesday but was on track for its biggest two-month fall in more than 20 years as German fiscal spending plans boosted the euro, while U.S. economic policies undermined investor confidence in the greenback.
The common currency jumped in early March as German parties, after decades of austerity, reached a deal to sharply increase public spending, boosting growth expectations for the euro area’s biggest economy.
In early April, investors rushed into safe-haven currencies such as the yen and the Swiss franc, but also the euro, as U.S. President Donald Trump announced tariffs that triggered fears of a full-blown trade war and a sharp global economic slowdown.
The U.S. dollar index DXY, a measure of the greenback’s value relative to a basket of foreign currencies, strengthened 0.25% to 99.28 on Tuesday after falling 0.58% the previous day.
It was on track for a 7.7% fall in March and April, the biggest two-month drop since May 2002.
The euro EURUSD was down 0.38% at $1.1379, but remained on track for its largest monthly gain against the dollar in more than two years as investors flee U.S. assets and search for alternatives in Europe.
“There are many structural factors that have supported the dollar in the past decades. I don’t think they will get destroyed so easily,” said Stephen Jen, chief executive officer and co-chief investment officer at Eurizon SLJ Capital.
“The euro-dollar can go higher to 1.20-1.25, but that has always been the fair value according to our calculations.”
April 29, 2025 at 11:52 am #23348April 29, 2025 at 11:26 am #23347April 29, 2025 at 11:06 am #23346April 29, 2025 at 10:50 am #23345Treasury Secretary Bessent says it’s up to China to de-escalate trade tensions
The comments come with markets on edge over the direction of tariffs. – By Jeff Cox
April 29, 2025 at 10:33 am #23344
US OPEN
US equity futures & USD modestly firmer with focus on reports of Trump easing auto tariff impact, Canada’s Liberals win election
Good morning USA traders, hope your day is off to a great start! Here are the top 6 things you need to know for today’s market.
6 Things You Need to Know
• US President Trump is expected to soften the impact of his automotive tariffs, according to WSJ citing sources.
• European bourses are mixed, whilst US equity futures trade incrementally higher, ahead of a slew of earnings.
• USD attempts to claw back some of Monday’s losses, CHF & JPY lags whilst the Loonie fares better post-election.
• Canada’s ruling Liberals, led by Mark Carney, won the national election but will need to form a minority government.
• Fixed benchmarks are relatively contained into a packed US session.
• Crude complex is on the backfoot, continuing recent losses, while base metals diverge.
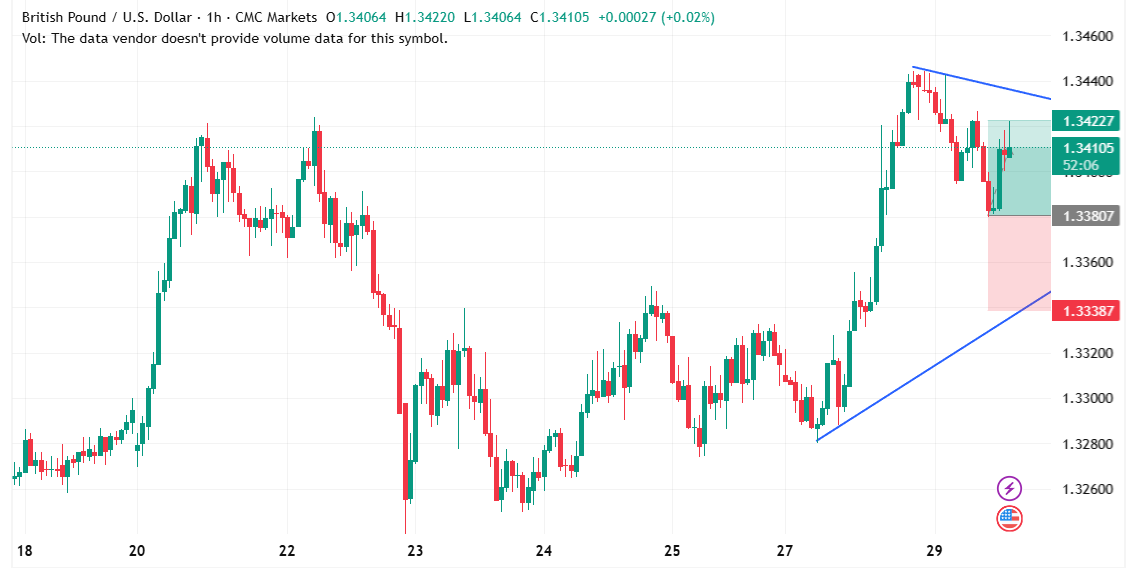
April 29, 2025 at 9:16 am #23343GBPUSD 4 OUR CHART – Sticky zone

At this time of day I like to focus on what I call the flavor of the day, which is the currency outperforming (or underperforming) but other than a flat USDCAD, there is nothing that stands out.
In GBPUSD, 1.34-1.35 is l;ikely to be a sticky zone where 1.3450 will dictate whether it can go after the upper end.
On the downside, key support is not until 1.3233-63 so it would take a big move to negate the current leg up. Using shorter term charts, supports are at 1.3393 (intra-day low) and 1.3330.
April 29, 2025 at 9:07 am #23341XAUUSD 4 HOUR CHART – Gold Trapped for now

Bulls will not give up the current battle unless 3250-60 is firmly broken while on the other side, a move above 3370 would be needed to put 3500 back on the radar.
This leaves 3260-3350/70 as the current range where 3300 seems to be pivotal in setting the tone.
April 29, 2025 at 9:01 am #23340Using my platform as a HREATMAP shows …

… the dollar trading a firmer but still down on the week as yesterday’s sell-off has not followed through.
USDCAD is about unchanged after a choppy overnight session following the Canadian elections where a Liberal win with a minority government as seen as the least desirable outcomne.
GOLD is down after not following through on yesterday’s rebound
Stocks are up a touch
The Trump administration said it plans to announce measures as early as Tuesday to ease the impact of tariffs on imported cars and car parts to give automakers more time to relocate production to the United States.(NYT)
Looking ahead
US data: Trade balance, JOLTS (job openings), Consumer Confidence
Watch for Bessent and Lutnick headlines but what it is what Trump says that carries more weight with markets.
Month end on Wednesday.
April 29, 2025 at 6:38 am #23338April 28, 2025 at 10:35 pm #23337A week ago: ““He will hopefully do the right thing – the right thing is to lower interest rates, so we’ll see what happens,” Trump
April 30: adv GDP exp 0.4%
May 2 NFP exp 130K
May 7 : FOMC
which means that the FED is in blackout as of the 26th BUT …d u think trump already knows the gdp and nfp numbers , coz judging from his screams at jerome to lower rates he should. coz if those numbers are crappier than expected donald holds jerome’s balls: see… I told you to cut! coz those releases are inside FOMCs blackout.
Earlier President Trump granted The Atlantic an intreview ‘I Run the Country and the World’
April 28, 2025 at 10:07 pm #23336April 28, 2025 at 9:27 pm #23335April 28, 2025 at 9:19 pm #23334THIS WEEK’S MARKET-MOVING EVENTS (all days local)
Next week will be significant for Europe’s largest economies, with Germany, Italy, and the Eurozone releasing their first-quarter GDP data amid uncertainty over trade tariffs and sluggish growth expectations. Germany recently downgraded its growth forecast to zero percent, reflecting ongoing economic challenges. Additionally, consumer confidence data for Germany and Italy will provide further insights into economic sentiment, which remains cautious amid rising inflation concerns, prompting potential stagflation discussions.
In the U.S., markets are bracing for first-quarter GDP and employment reports. Forecasts vary considerably due to uncertainties related to trade and tariff policies. The Atlanta Fed predicts a GDP contraction, while other regional Fed forecasts remain modestly positive. Payroll figures for April will reveal whether recent federal layoffs are starting to impact the private sector, adding to broader concerns about slowing job growth and consumer spending.
In Asia, April PMI data will offer the first indicators of how recent tariff escalations are affecting economic activity, with particular attention on China. Australia’s upcoming inflation and retail data will influence policy discussions at the Reserve Bank of Australia’s May meeting, while South Korea’s industrial production and trade figures will highlight the region’s economic resilience amid global trade tensions.
Econoday
April 28, 2025 at 8:23 pm #23333GME – GameStop Corporation Daily
It has been long time that I even looked at this one ….
And what do we have here – looks to me as yet another “ Come Kitty Kitty, come” situation
Resistance is at 28.00 now
Failure at it would send GME to 22.35 at first, and then it is all on 18.65 to hold …or not …
My distaste for this stock aside – let’s be professional…
If Kitty stock surmounts 28.00 and holds onto winnings, it should test 30.50, and whatever the result on it, the situation would turn Bullish for GME.
Is it because of that Crypto deal company did , or there are some other fundamental reasons behind it, this time it looks natural and not Viral Franzy based…
 April 28, 2025 at 8:13 pm #23331
-
AuthorPosts


- You must be logged in to reply to this topic.
Search
© 2024 Global View