
- This topic has 28,268 replies, 54 voices, and was last updated 1 hour, 9 minutes ago by GVI Forex 2.
-
AuthorPosts
-
August 12, 2025 at 3:11 pm #28856August 12, 2025 at 3:09 pm #28855August 12, 2025 at 2:55 pm #28854August 12, 2025 at 2:50 pm #28853
What’s hot and what’s not?
What’s hot?
EUR and GBP up vs the USD, others now about flat on the day after falling earlier.,
US stocks are firmer following CPI
What’s not?
The USD after President Trump’s threat to sue Fed Chair Powell put a nail in its rally attempt after the dip on CPI.
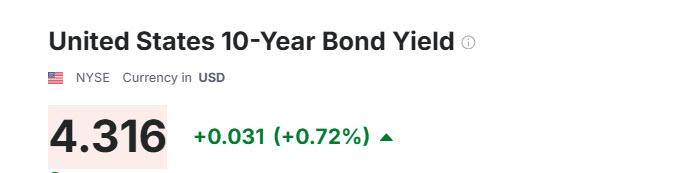
US bonds down (yields up)’
GOLD is down, continues to struggle in attempts to regain a bid
 August 12, 2025 at 2:34 pm #28852August 12, 2025 at 2:19 pm #28851August 12, 2025 at 2:04 pm #28850August 12, 2025 at 2:00 pm #28849August 12, 2025 at 1:49 pm #28848August 12, 2025 at 1:47 pm #28847August 12, 2025 at 1:30 pm #28846August 12, 2025 at 1:18 pm #28845August 12, 2025 at 1:12 pm #28844August 12, 2025 at 1:12 pm #28843
maybe a better “essplainer” than my earleir one about player reaction
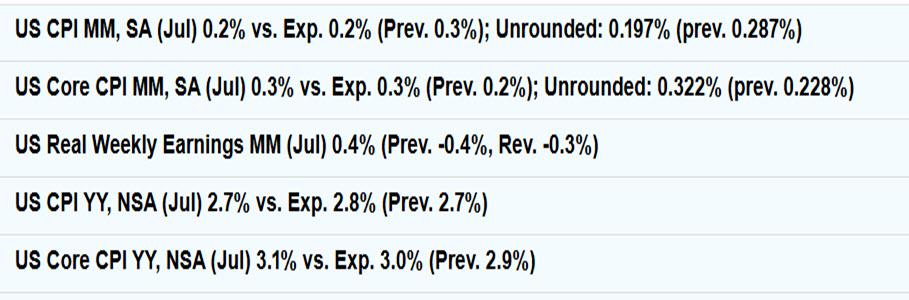
curtesy ZH:“Rate-Cut Odds Soar As US Consumer Prices Once Again Reject Trump Tariff Terror”
So, not exactly the screaming spike in prices that Democrats interviewed by UMich have hallucinated about?August 12, 2025 at 12:59 pm #28842August 12, 2025 at 12:54 pm #28841August 12, 2025 at 12:44 pm #28840… How reliable is US CPI even though the market will react to it? …
what a lesson this morning about how markets reacts to how-ever-doubtful numbers eh ?
I suspect the two yakkers have a good reason to yak some two hours after the release
– it gives them time to watch player reaction to the release and how players adjust their odds
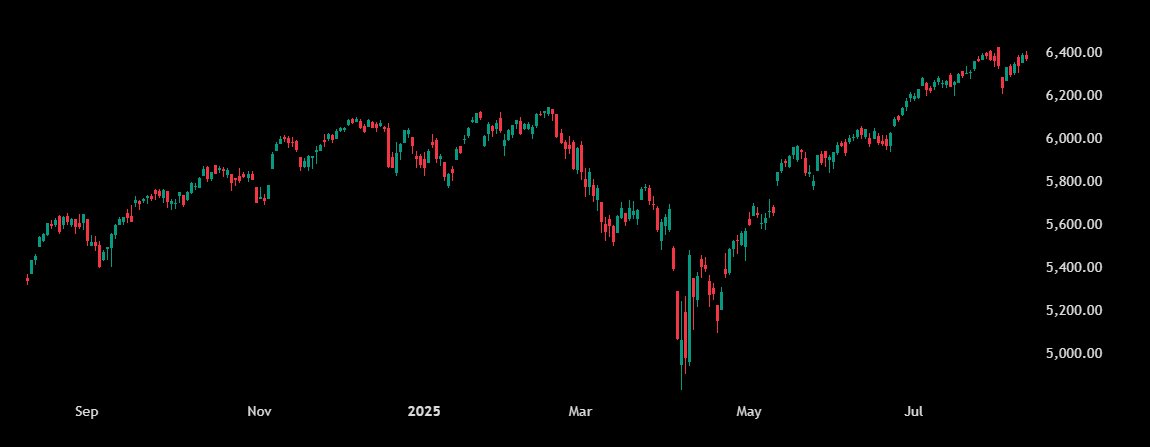
– they probably have two versions of of their yaks at the ready; all about their propaganda for the market to try to influence FED’s continued credibility even as their chair may have whithered his.August 12, 2025 at 12:36 pm #28839August 12, 2025 at 12:36 pm #28838August 12, 2025 at 12:32 pm #28837August 12, 2025 at 12:31 pm #28836Why 6,500 can be a launching pad for the S&P 500
In thin summer markets, round numbers become magnets, says a popular newsletter author
Underweight positioning could fuel an extension of the stock-market rally.
The S&P 500 sits a fraction shy of its record close. Inevitably the altitude makes some twitchy, pointing to perhaps 6,500 where the air may be too thin to sustain bullish life forms.
Hedge fund net leverage, for example, is currently at its 3-year median, and therefore not extended.
According to Goldman Sachs, hedge fund clients last week sold indices and exchange traded funds at the fastest pace in four months. “That’s not all-in like people would expect, that’s them still hedging into highs like they’re expecting the puke any day now”
Commodity trading advisors’ long positions are elevated but not maxed out
And volatility control funds – funds that adjust their positions depending on how higher or low volatility is – are still mechanically adding exposure because realized vol just keeps bleeding lower, while even the activity of retail investors points to steady buying rather than the fear of missing out.
Furthermore, earnings season has left valuations looking less stretched. Twelve-month forward S&P earnings estimates are up 3.6% in the past month – the strongest seasonal start in years. These aren’t just companies clearing some artificially low bar; they’re actively reshaping the forward outlook
In summary, the market is in an under-owned grind higher, going up because few believe that it should.
And that’s exactly why 6,500 won’t be a ceiling – it could be a floor that we rocket past on our way to something much higher. You don’t get a real top when half the street is still positioned for a disaster, you get melt-ups.”
And this is more likely to occur during periods of lower trading volumes, such as the late summer.
 August 12, 2025 at 12:22 pm #28835
Nikkei – FTSE – DAX
The Nikkei 225 Index Closes 2.21% Higher
In Tokyo, the Nikkei 225 Index went up by 923 points or 2.21 percent on Tuesday.
Top gainers were Mitsui Mining & Smelting (13.30%), CyberAgent (10.67%) and Inpex (7.09%).
FTSE 100 Rises for 2nd Session
The FTSE 100 traded higher on Tuesday, building on Monday’s 0.4% gain, driven by a record 19% surge in Spirax shares after the steam flow engineer posted better-than-expected earnings and maintained guidance.Citi called the results “encouraging,” with scope to beat forecasts, offering reassurance after years of declines.
DAX Moves With Caution
The DAX in Frankfurt opened slightly higher on Tuesday but pared gains to trade near the flatline around 24,070, amid caution ahead of key economic releases from both Germany and the US. Initially, market sentiment was boosted by optimism that the extended 90-day truce between the US and China could lead to a meaningful trade agreement. August 12, 2025 at 12:17 pm #28834
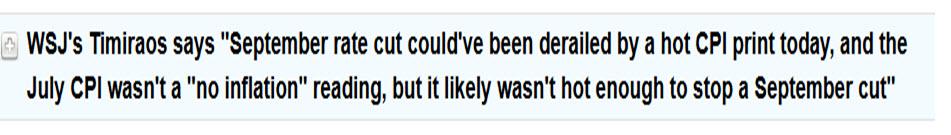
CPI at bottom of hour
overall expectations are for up readings, meaning hard times for low income folk
but also a tickle of the expert minds at the FED eyeballing slowing labour market.Helping the market meddling policymakers is the market currently pricing 85% odds of sept 25 bps cut.
So … if the data comes in hotter than expectations, odds of FED cutting will come down some thus giving the dlr bit of a philip. Coming lower than expectations should see the dollar get whacked some.
After the CPI numbers are scheduled two FED yakkers
10:00 – non-voter hawk barkin on “economy”
10:30 – voter hawk schmid – monetar policy and econ outlookAugust 12, 2025 at 11:58 am #28833August 12, 2025 at 11:50 am #28832August 12, 2025 at 11:03 am #28831August 12, 2025 at 10:57 am #28830How reliable is US CPI even though the market will react to it?
Staffing Shortages & Reduced Data Collection
Due to federal hiring freezes and budget cuts, BLS has scaled back CPI price collection, suspending sampling in cities like Lincoln (NE), Provo (UT), and Buffalo (NY)
BLS maintains that these reductions have minimal impact but do you believe it?
Greater Reliance on Imputed Data
With fewer price observations, BLS must fill gaps using imputation by estimating missing data with models or nearby price sets. The share of imputed prices has spiked: from around 10–15% typically to nearly 30% in certain months
This elevated reliance on estimates may distort the accuracy of the CPI, especially amid volatile economic conditions
Commissioner Firing and Data Credibility
The recent firing of BLS Commissioner Erika McEntarfer, following a weak jobs report, has triggered widespread concern over political interference in what is supposed to be a nonpartisan statistical agency
Economists warn that such actions can erosion public trust, hamper survey response rates, and weaken data quality, especially for key metrics like CPI (from the internet)
 August 12, 2025 at 10:29 am #28829August 12, 2025 at 10:27 am #28828August 12, 2025 at 10:22 am #28827
-
AuthorPosts





- You must be logged in to reply to this topic.
Search
© 2024 Global View