- This topic has 28,558 replies, 54 voices, and was last updated 6 hours, 14 minutes ago by GVI Forex 2.
-
AuthorPosts
-
September 2, 2025 at 12:34 pm #30064September 2, 2025 at 12:26 pm #30063September 2, 2025 at 12:24 pm #30062September 2, 2025 at 12:22 pm #30061September 2, 2025 at 12:05 pm #30060
Euro Slides as European Bond Yields Surge on Fiscal Concerns
The euro slipped toward $1.16 on rising European government bond yields, as investor focus shifted to mounting fiscal concerns.
French and German 30-year yields hit levels not seen since 2011, during the eurozone sovereign debt crisis.
Germany’s medium-term finance plan foresees roughly €500 billion in net new borrowing through 2029 to fund increased infrastructure and defense spending.
In France, concerns over the country’s debt burden are a key factor behind the prime minister’s confidence vote scheduled for next week.
Meanwhile, eurozone inflation accelerated to 2.1% in August, slightly above both market expectations and the ECB’s 2% target, reinforcing forecasts that the central bank will keep interest rates unchanged at next week’s meeting.
 September 2, 2025 at 12:02 pm #30059
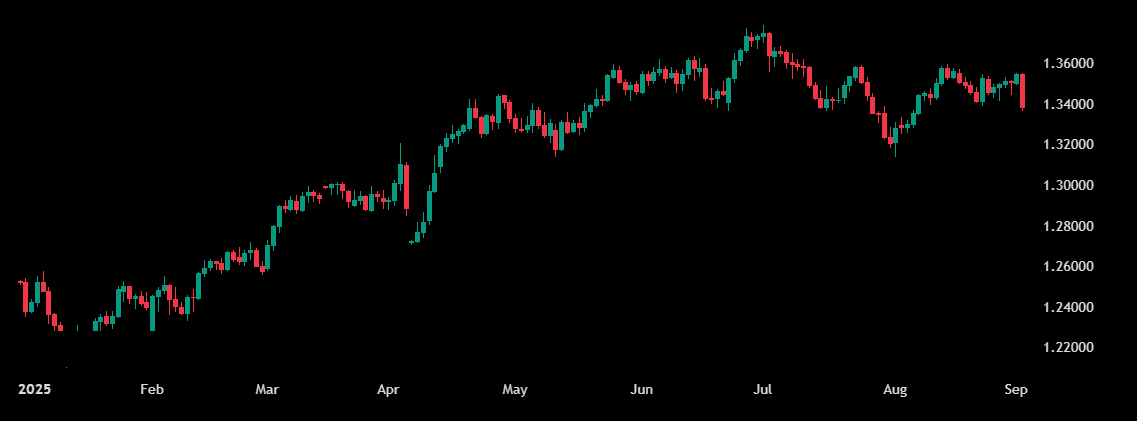
Sterling Slides as Gilt Yields Spike
The British pound fell below $1.34 on Tuesday, its weakest level since early August, amid a sharp rise in long-dated UK government bond yields due to concerns over the country’s fiscal outlook.
The yield on the 30-year gilt climbed to its highest since 1998, intensifying pressure on Chancellor Rachel Reeves ahead of the Autumn Budget and further squeezing already limited fiscal space.
Reeves is widely expected to announce tax increases to rein in the deficit.
Political attention also turned to Westminster, where Prime Minister Keir Starmer unveiled a cabinet reshuffle on Monday.
Meanwhile, investors are focused on the Treasury Committee’s questioning of Bank of England policymakers for signals on the path of interest rates and any potential adjustments to the central bank’s quantitative tightening program.
 September 2, 2025 at 11:59 am #30058September 2, 2025 at 11:58 am #30057
Traders turn to the dollar as yields blowout finally takes a toll on markets
It seems like the blowout in bonds (yields surging higher) is seeing a rush to cash. Margin calls being hit? We’re also starting to see equities get struck down as well with S&P 500 futures now lower by 0.6% on the day.
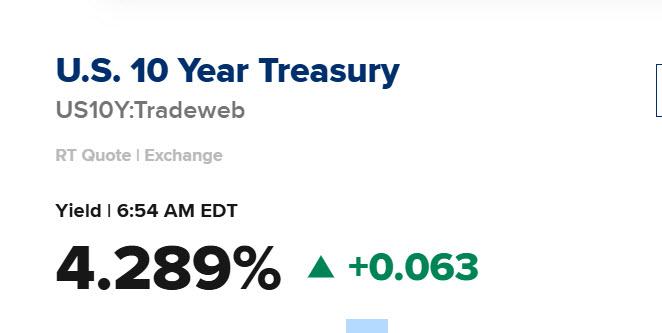
The gilts market made headlines earlier when 30-year yields, currently at 5.69%, ran up to its highest since 1998. The move higher has been coming all through August and it’s also the same case for the likes of Europe, Japan, and the US. However, today looks to be the straw that breaks the camel’s back as we see broader market implications hit.
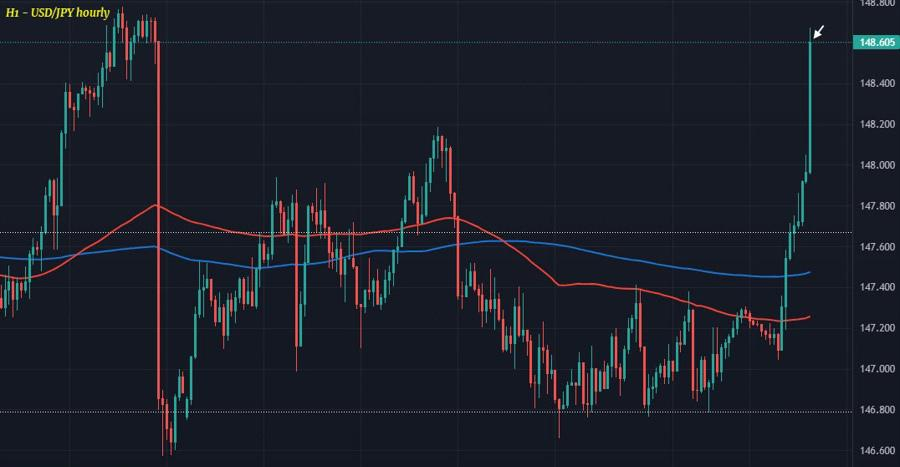
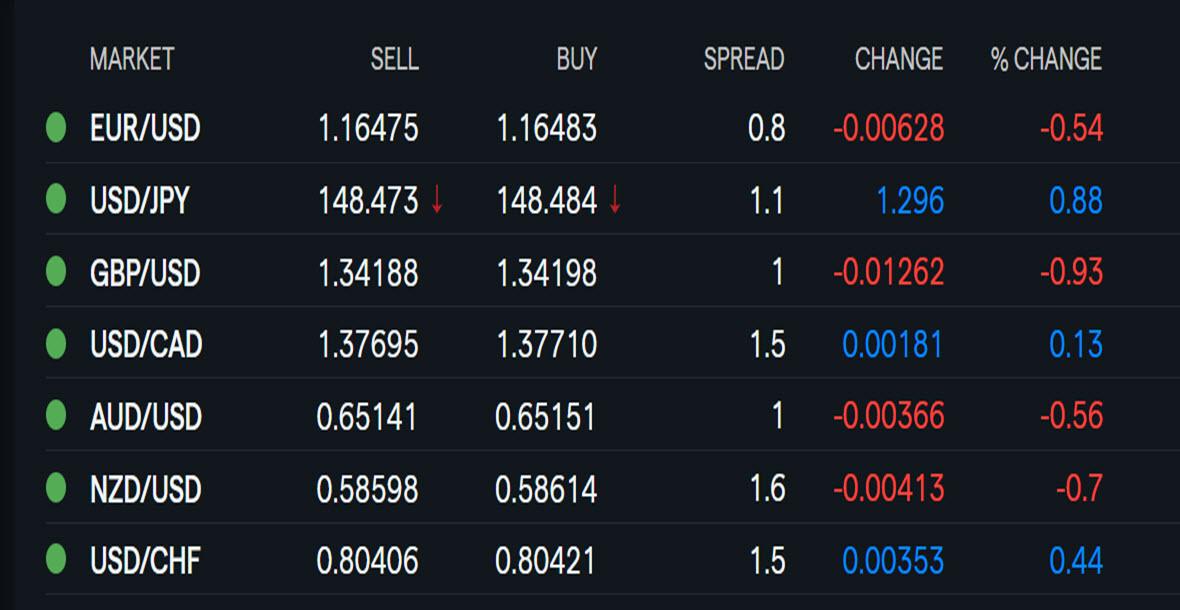
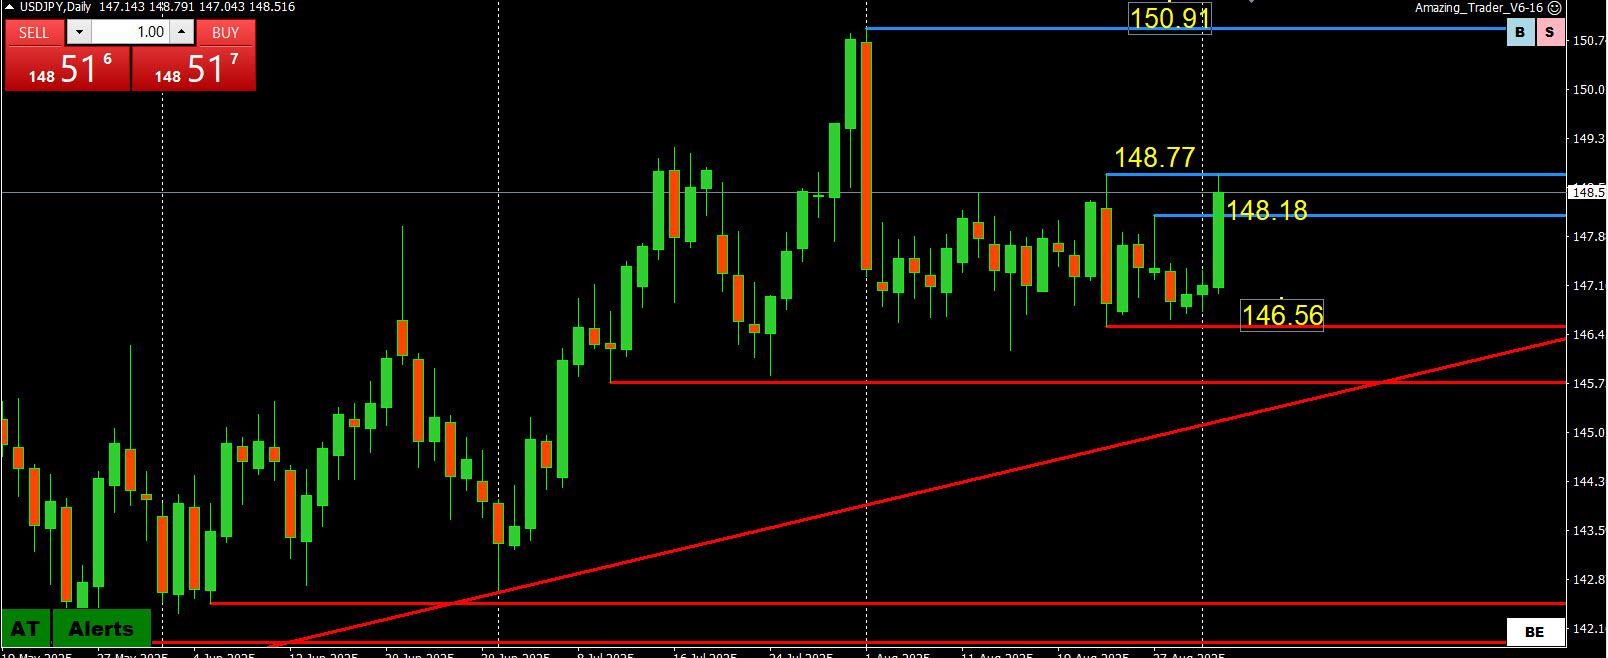
In response, the FX market is seeing strong bids into the dollar pile in. EUR/USD is down 0.6% to 1.1640 and USD/JPY is up 1% on the day to 148.60 currently.
What looked like a potentially quiet session in Europe has turned out anything but that at the moment.
GBP/USD is also now down 1% to 1.3405 and even USD/CHF is more bid, up 0.3% on the day to 0.8030 currently. In turn, risk currencies are also lower with AUD/USD down 0.7% to 0.6505 on the day.
As much as we are seeing spillovers to broader markets, it’s best to keep a level head on the situation at hand. A call for correction in equities is definitely something to be wary about especially if long-end yields continue to blow up in the week(s) ahead.
The US yield curve continues to steepen and if that’s a sign of a policy mistake by the Fed, it’s not exactly one that will be all too supportive for the dollar amid ongoing political pressures and a confidence/credibility hit.
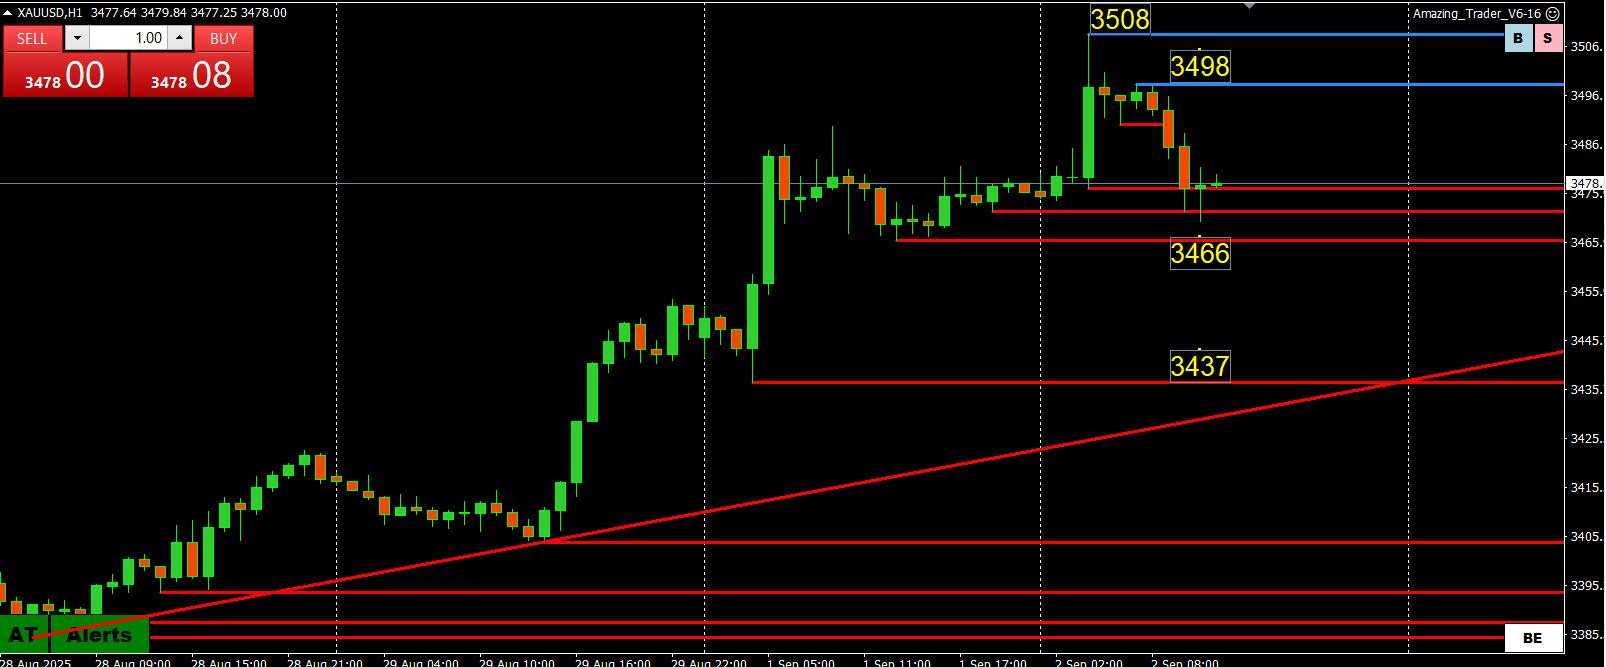
And despite the initial setback to gold we’re seeing at the moment, the precious metal stands to reason to shine in this sort of environment. So, do keep an eye out for dip buyers in trying to seize the opportunity here once the dust settles.
 September 2, 2025 at 11:01 am #30056September 2, 2025 at 10:11 am #30055September 2, 2025 at 9:50 am #30054September 2, 2025 at 9:31 am #30053
GBPUSD
The biggest loser today
You can see by this chart why 1.3390 is important as there is big void below it
Low so far 1.3375 after stops run…needs to trade above 1.3390 to cool the risk… treat any bounce, should one occur, as retracement while it trades below 1.35
Below 1.3390 is very bearish.
GBPUSD DAILY CHART
 September 2, 2025 at 9:31 am #30052
PLAN B
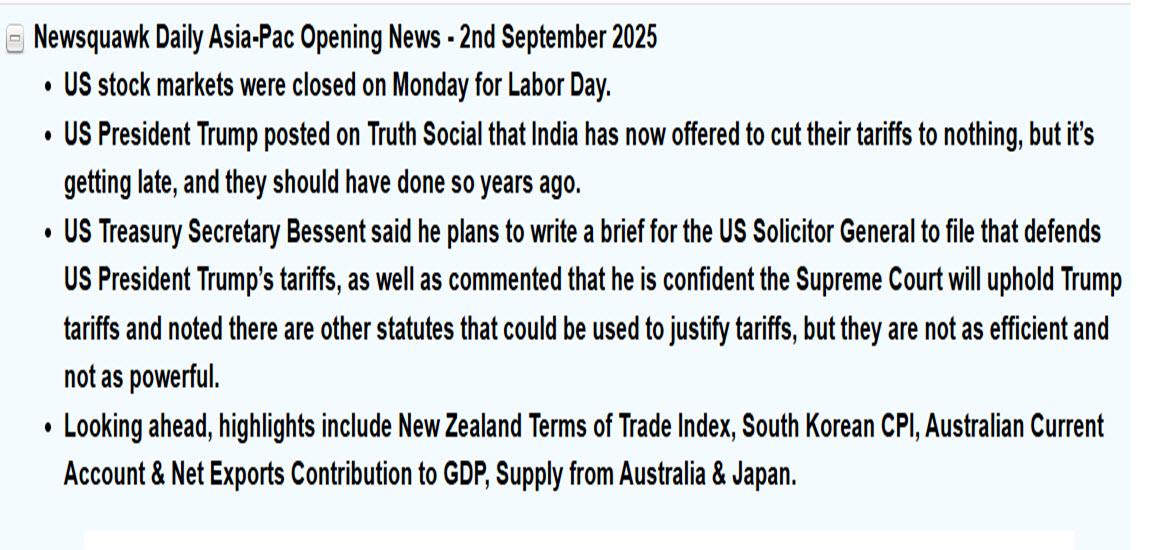
(a betting opportunity)Bessent expects Supreme Court to uphold legality of Trump’s tariffs but eyes Plan B
September 2, 2025 at 9:18 am #30051September 2, 2025 at 9:13 am #30050September 2, 2025 at 8:57 am #30049Using my platform as a HEATMAP shows,,,
.. the start of post summer trading fids markets in a risk off mood with both the odd mic of both GBP and JPY both underperforming> usd is getting a bid from a flight to safety< which has not been its role lately>
On order of strength vs the USD
1. CAD
2. CHF
3. EUR
4. AUD
5. NZD
6. JPY
7. GBP
 September 2, 2025 at 8:43 am #30048September 2, 2025 at 8:16 am #30047September 2, 2025 at 8:16 am #30046September 2, 2025 at 12:51 am #30045September 2, 2025 at 12:46 am #30044September 1, 2025 at 10:24 pm #30043September 1, 2025 at 8:00 pm #30042September 1, 2025 at 7:57 pm #30041
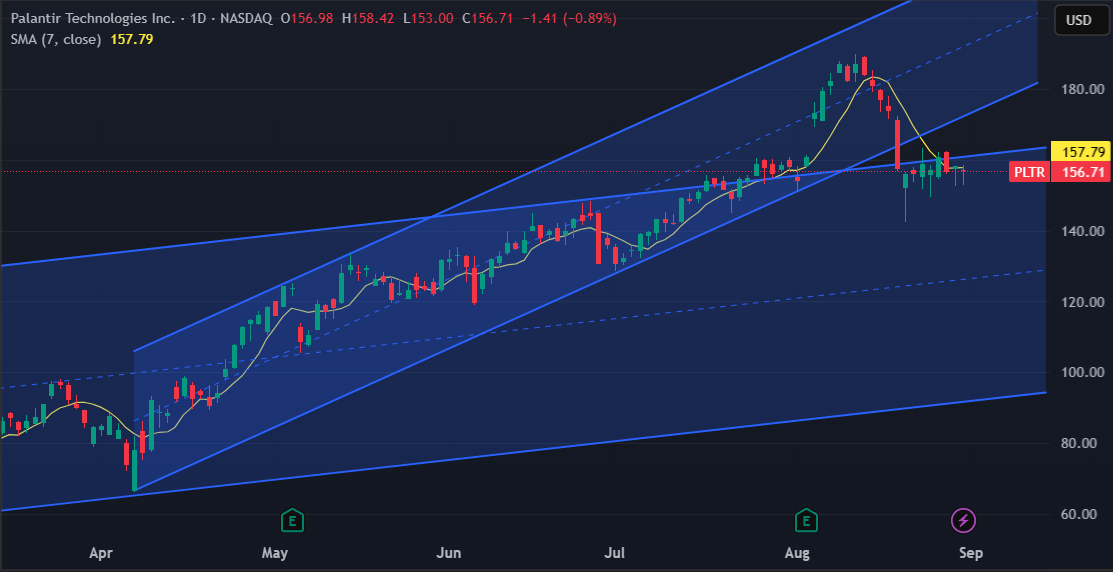
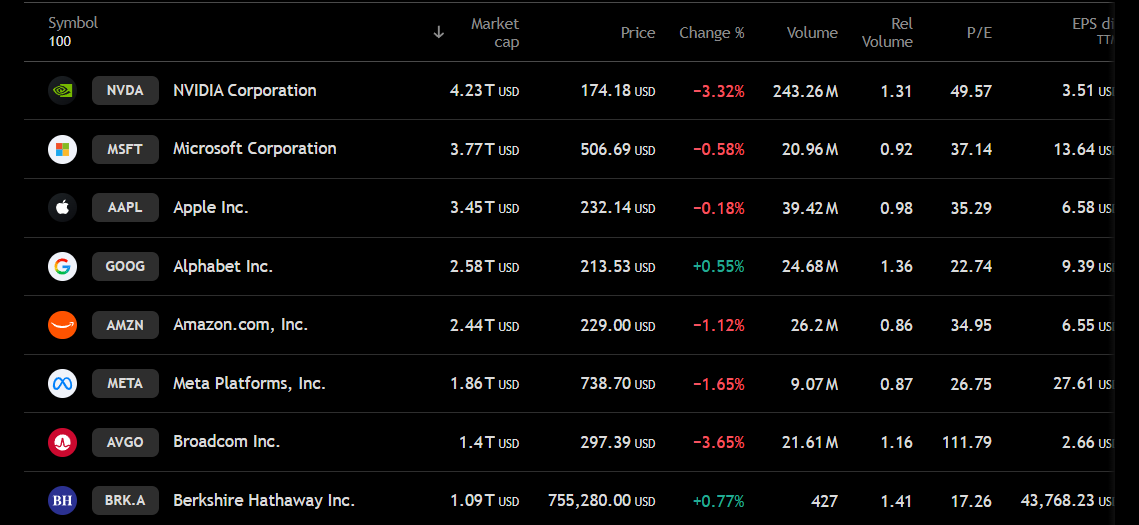
Palantir Stocks – PLTR
Palantir’s AIP-Led Growth Places It Ahead in the AI Race
Palantir Technologies PLTR continues to stand out as one of the most compelling plays in the artificial intelligence sector, thanks to the explosive adoption of its Artificial Intelligence Platform (AIP). With enterprises seeking immediate, operational-ready AI tools, PLTR has positioned itself as a leader by delivering turnkey solutions that integrate seamlessly into existing workflows. This capability is a key differentiator, enabling organizations to deploy advanced AI systems without lengthy development cycles, a feature that fuels rapid adoption and customer loyalty.A major driver of Palantir’s momentum is its expanding U.S. commercial business. In the most recent quarter, domestic commercial revenues surged at a staggering pace, reflecting the accelerating embrace of AI-driven decision-making among corporations.
 September 1, 2025 at 7:53 pm #30040
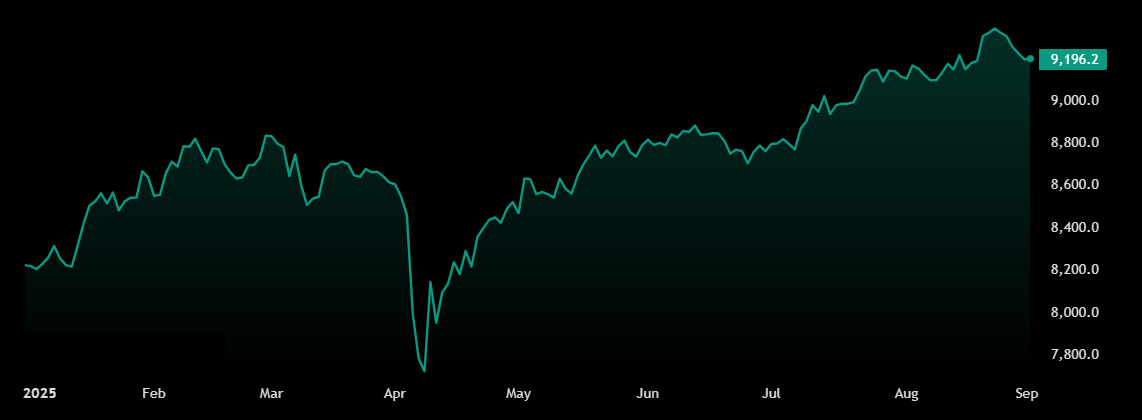
FTSE 100 Index Ends 0.10% Higher at 9196.34
The FTSE 100 Index is up 9.00 points or 0.10% today to 9196.34
· Largest one day point and percentage gain since Friday, Aug. 22, 2025
· Snaps a four trading day losing streak
· Off 1.34% from its record close of 9321.40 hit Friday, Aug. 22, 2025
· Up 45.10% since the pre-Brexit vote level of 6338.10 hit Thursday, June 23, 2016
· Off 1.34% from its 52-week high of 9321.40 hit Monday, Aug. 25, 2025
· Up 19.75% from its 52-week low of 7679.48 hit Wednesday, April 9, 2025
· Rose 9.95% from 52 weeks ago
· Off 1.34% from its 2025 closing high of 9321.40 hit Monday, Aug. 25, 2025
· Up 19.75% from its 2025 closing low of 7679.48 hit Wednesday, April 9, 2025
· Year-to-date it is up 1023.32 points or 12.52%
 September 1, 2025 at 7:50 pm #30039September 1, 2025 at 7:47 pm #30038
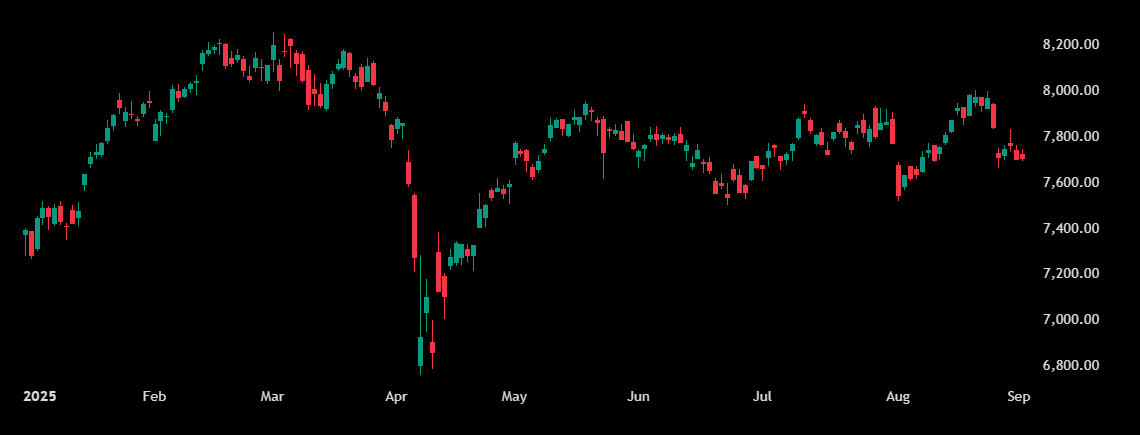
CAC 40 Starts the Week Flat
The CAC 40 index edged marginally higher to close at 7,708 on Monday, as markets turned cautious ahead the confidence vote and US data later this week.
France’s manufacturing PMI unexpectedly returned to expansion at 50.4 in August from 48.2 in July, with employment rising at the fastest pace in over three years and contractions in output and new orders easing.
On the negative side, political and fiscal risk has risen ahead of the September 8 confidence vote called by Prime Minister François Bayrou over his contested 2026 budget measures, prompting markets to reprice a higher risk premium.
Adding to the pressure are rising input cost inflation in manufacturing, weaker export momentum, particularly to the United States, and global rate cues with a key US jobs report due later in the week, leaving the net effect muted.
Several large caps such as Airbus, Stellantis, and Société Générale gained between 0.7% and 1.6%, while Hermès, Thales, and ENGIE slipped between 0.5% and 1.3%.
 September 1, 2025 at 7:39 pm #30037September 1, 2025 at 7:32 pm #30036September 1, 2025 at 7:28 pm #30035
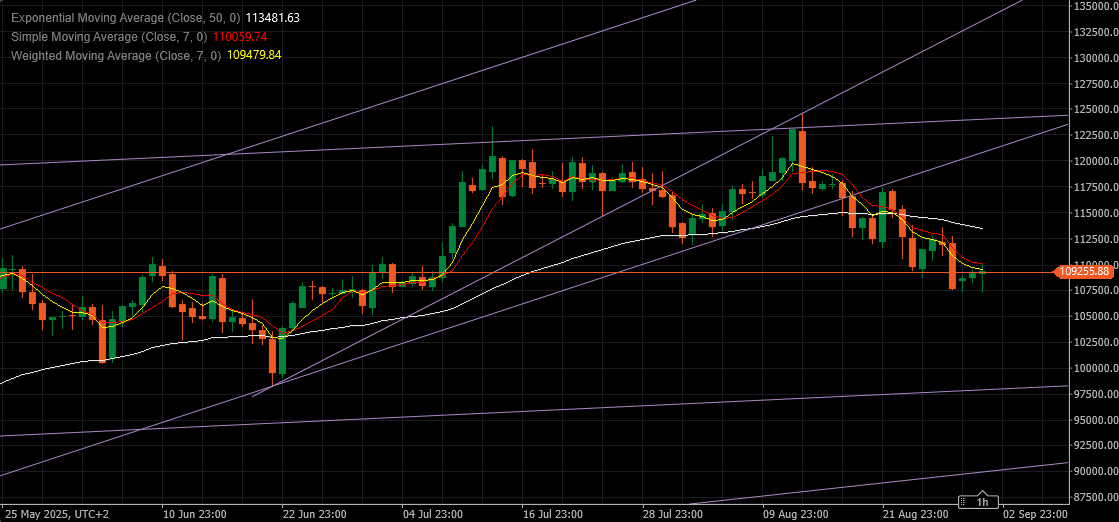
BTCUSD
Bitcoin is finding support in 107.500 area and now we might be testing some resistances.
Resistances: 109.925, 113.500 & 115.625
Supports: 108.200 & 107.500
113.500 will be a turning point – if taken out opens a way for 125K, but if proves to be stubborn resistance BTC will be visiting 105.000
-
AuthorPosts


- You must be logged in to reply to this topic.
Search
© 2024 Global View